Some common economic fallacies, such as ‘immigrants take our jobs’ the broken window fallacy and the Luddite fallacy on the role of new technology.
1. Luddite Fallacy – New technology causes unemployment

This is the argument that new technology causes job losses. In the nineteenth century, it referred to workers who smashed new spinning machines – fearing jobs would be lost. We now look back and think they are mistaken. But, at the same time, we fear the modern equivalent of new technology (e.g. automation and artificial intelligence) will lead to job losses.
- There used to be one million people employed as typists in the US; the personal computer caused most jobs to disappear, but it doesn’t mean there is an additional 1 million unemployed typists were re-employed in different kinds of jobs.
- The UK used to have 1 million people employed in the coal industry; now hardly anything. Higher productivity means different kinds of jobs are created.
- New technology can create jobs in making the technology, but also if they reduce the cost of production, it effectively increases real incomes so people can spend elsewhere in the economy.
- However, it is worth pointing, new technology can cause temporary structural unemployment and those who lose their jobs may struggle to find new employment. Some will lose out in the short-term from the introduction of AI.
See: The Luddite Fallacy
2. Lump of Labour Fallacy – Immigration causes Unemployment
It is an argument often repeated. It goes something like this. “Immigrants who come over here are willing to work for lower-paid jobs and thus they create lower wages and unemployment for local people.”
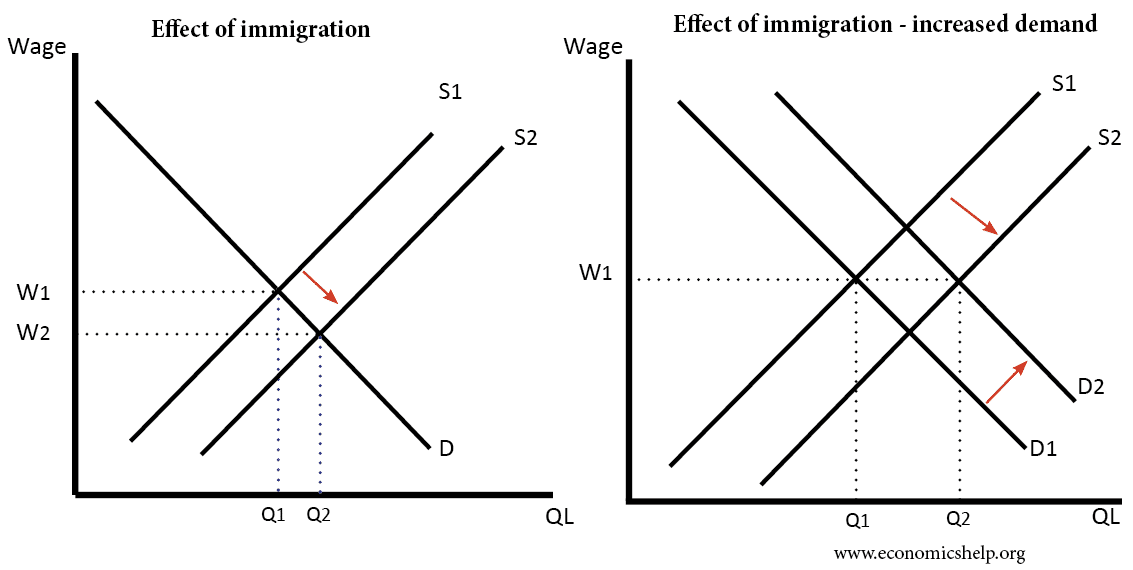
- If immigration just increased the supply of labour (on left) wages would fall.
- But immigrants also increase demand in the economy. This means that they buy more goods and create additional demand in the economy. They provide labour supply and increase labour demand. So all being equal, wages will be unaffected.
- From one perspective, an increase in the labour supply may push down wages. This is especially true if migrants are keen to accept lower wages (e.g. willing to bypass traditional union bargaining). However, net migration doesn’t have to push down wages. The massive immigration into the US, during the twentieth century was consistent with rising real wages.
- If immigration caused unemployment why did America not have high unemployment during times of mass immigration? Because the immigrants created as many jobs as they took.
- Often immigrants take jobs that native workers just don’t want to do. – You won’t see big multinationals cueing up to stop immigration.
- Furthermore, immigrants tend to be of working age. Therefore they tend to contribute more tax than receive in benefits. Without immigration, US demographics would have a larger % of dependent old people.
- However, it is worth pointing out. If migration is weighted towards unskilled workers, then this can reduce wages of native unskilled workers
- Lump of labour fallacy
3. The Zero-Sum Fallacy
This is the belief that one person’s gain must be another’s loss. It was a critical part of mercantilist thinking that dominated very early economics. It led to the idea if you wanted to get richer, you needed to take gold and other assets from other countries. In other words, welfare was limited.
The early economists like Adam Smith and David Ricardo suggested trade between countries could make both better off. If you sell surplus to another country, you can gain revenue that enables you to buy their imports. See: Zero-Sum games in economics
Voluntary exchange creates mutual benefit, so trade and markets often expand total welfare.
4. War is good for the economy

This fallacy is deeply embedded in many people’s minds. One reason is that it was felt that the Second World War ended mass unemployment in the US and UK. To some extent, it is true that nemployment fell because of the Second World War. However, war is not necessary to solve unemployment. The government could have intervened to create jobs through public work schemes.
- War does create more output, but only in some industries related to war. Arms manufacturers do very well out of the war. But the total output of the economy doesn’t increase instead, there is a change in economic priorities. Resources are diverted from peaceful industries to industries for creating the mechanisms of war. This is similar to the broken window fallacy.
- If a butcher’s window is smashed, the window repairer sees new work. He gains more income. But the broken window hasn’t increased economic welfare. It just means the butcher has to spend money repairing a window rather than investing in a bigger premise.
- War involves a very large opportunity cost – money spent on bombs cannot be used to build hospitals.
- Increase in government spending for wars creates either taxes and or higher debt payments. This is a burden on current and future taxpayers.

- Note The UK and US are still paying off debt from the Second World War.
4. Tax Cuts make people work harder
- Ronald Reagan’s economic adviser, A.Laffer told him something along the lines of “cut taxes” and you can increase total tax income. This theory is based on the Laffer curve which states that if taxes are 100% people won’t work. Therefore if you cut taxes more people work and you can increase tax revenue.
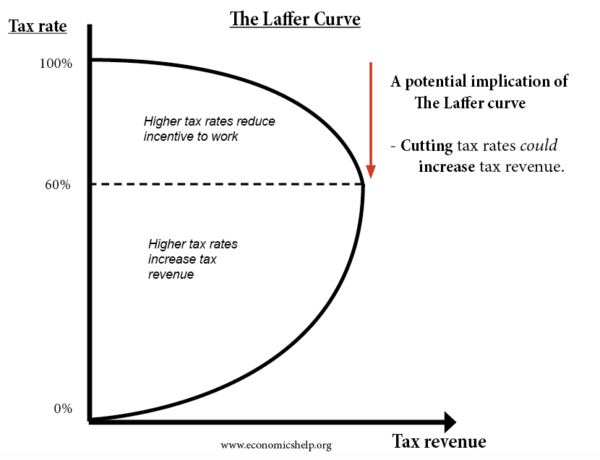
- The problem is that this may work if you cut taxes from 95% to 90%. But when you cut income tax from 25% to 23% it doesn’t make any difference.
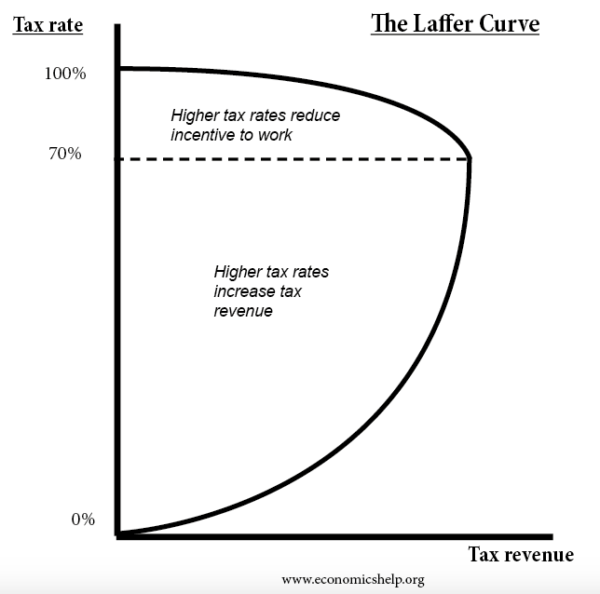
- Some people want a target income of say £20,000. Thus if taxes fall they can earn the same by working less. Empirical evidence suggests there is little if any supply-side incentive for cutting US or UK tax rates.
- Evidence suggests that the Laffer curve kicks in after a marginal tax rate of 70 or 80%
5. Tariffs protect jobs
Tariffs appear to protect domestic jobs by making imports more expensive, allowing local producers to sell more. In the short run, some jobs may indeed be saved. But this is only part of the story. When you look at the whole economy, tariffs destroy at least as many jobs as they protect, often more.
- Tariffs lead to higher price of imports. Higher prices leave consumers with less to spend elsewhere, reducing employment in other sectors.
- Firms that depend on imported inputs face higher costs and lose competitiveness. This was particularly noticeable for US car industry faced with higher tariffs on Canada and Mexico imports (2025)
- Trading partners often retaliate to tariffs by placing tariffs on the countries exports. This harms export industries that typically support higher-value jobs.
- Tariff protection reduces the incentives for firms to innovate and move into more competitive industry. Therefore, it can keep workers in lower-productivity sectors rather than moving to areas of comparative advantage.
- In the end, the few jobs artificially “saved” are outweighed by the many jobs quietly lost across the economy, leaving overall employment either the same or even the higher.
6. Retaliate to tariffs
- The instinctive reaction of politicians is that if one country places a tariff barrier on our exports, we should respond by doing the same. However economic theory suggests that placing a tariff barrier on imports leads to a loss of economic welfare. And therefore, it is better not to retaliate.
- Retaliation may help one small domestic industry, but it causes costs to all consumers in the form of higher prices. There is a net welfare loss, that is not recovered by some domestic industries gaining benefits.
7. House prices never fall where there is a shortage of supply
True there is a shortage of supply in big cities like London and New York. However, this doesn’t mean house prices will always keep on rising. House prices can fall just like anywhere else. It just means that they will be higher on average than elsewhere in the country.

This shows that house prices in London rose the most, but they also had some of the biggest crashes in early 1990s and 2009/10
8. The Post Hoc Fallacy
The idea that something happened because of another event.
- After Trump placed tariffs on imports, US inflation rose. Therefore, tariffs caused inflation.
- This is not necessarily true. It may be that inflation primarily rose because of an increase in oil prices or excess demand in the economy.

Economic events often have multiple interacting causes, so correlation ≠ causation.
In this diagram gold prices rose because of inflation in 1980. and gold prices fell, when inflation came down. But, in 2025, we can see gold continues to rise even when inflation falls, suggesting we can’t necessarily make an assumption based on two things.
9. “Exports Are Good, Imports Are Bad” Fallacy
It is often assumed a current account deficit is a bad thing, and exports are good. But, actually, it is imports which enable us to consume and enjoy more goods and services. If you restricted imports, you would restrict consumer living standards.
10. The Government Budget Fallacy (Equivalent to a Household)
Treating government finances like a household. It is a mistaken belief that a government should always manage its finances like a household.
Unlike households, governments can tax, borrow at scale, issue currency, and affect demand in the economy.

- This shows how the government deficit mirrors a private surplus. So a government deficit in a recession may be rational response to higher savings.
- Treating government budgets as if they face the same constraints as households ignores the role of fiscal policy, automatic stabilisers, and the fact that public spending can stimulate growth and increase tax revenues. In the Great Depression, efforts to reduce the budget deficit caused the depression to become bigger.
11. Free Lunch Fallacy
This is the belief that governments can provide benefits without costs—for example, people want government to increase spending on pensions, without realising there is an opportunity cost of taking resources from elsewhere in the economy (e.g. requires higher tax, higher borrowing or spending cuts elsewhere)
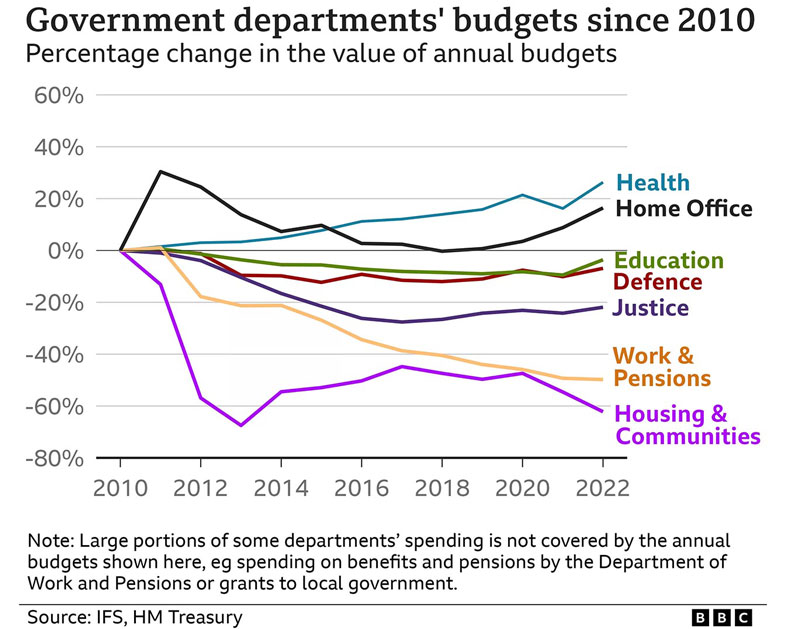
Health care spending increased in UK, but look at many departments which saw cuts.
12. The Fallacy of Composition
What is true for one individual is not necessarily true for everyone. In the great depression, Keynes noticed people saved more – which was an understandable personal decision. But, because everyone saved more simultaneously, it was bad for the economy in general, aggregate demand fell. Keynes called this the paradox of thrift.
Another example. A country should cut corporation tax to encourage more foreign direct inward investment. But, if one country cuts tax rates and everyone follows suit, there will be no change in inward investment, everyone just has lower corporate tax revenues.
13. Money illusion
House prices in the UK have increased from £10,388 in 1975 to £272,819 in 2025, a 2,600% increase.
But, the increase in real terms (adjusted for inflation) is nothing like as spectacular. Adjusted for inflation, house prices in 1975 would have been £136,683, closer to 100% increase

It is the same with workers getting big pay rise of 10% and feeling better off, but if inflation was 12%, they are actually worse off.
Related
About The Author
