Currently, the UK government has public sector debt of £2.6 trillion or 97.5% of GDP. But how much more debt could the UK take on before it leads to default? There is no exact answer; the amount of debt a government can borrow will depend on several factors.
- Cost of borrowing – debt interest payments and bond yields
- Domestic saving levels – high domestic saving will mean higher demand to buy government bonds.
- Rate of economic growth and state of economy – strong growth will lead to higher tax revenue in the future.
- Willingness of markets to buy debt – Do markets trust the government to maintain low inflation and not default?
- Central Bank policy towards inflation and buying debt. Can the Central Bank create money to buy bonds?
- External debt and balance of payments. If you borrow in foreign currency, then debt is much more problematic; if you borrow in your own currency, you have more latitude.
- What is the purpose of government borrowing? – For short-term crisis markets are more likely to lend, but you can’t borrow to keep paying for ever rising pension payments and an ageing population.
If we look at the government levels of debt, there is a big variation between Japan, at 250% of GDP and Denmark 30% of GDP

Ironically, the country with the biggest debt concern in this graph is Venezuela. Due to a collapsing economy, economic sanctions and falling oil prices, they have defaulted on their debt repayments. Japan’s situation by contrast, is not quite as bad as it looks. (though Japanese bond yields are rising, which makes it more interesting…
UK Debt History
Source: Reinhart, Carmen M. and Kenneth S. Rogoff, “From Financial Crash to Debt Crisis,” NBER Working Paper 15795, March 2010. and OBR from 2010.
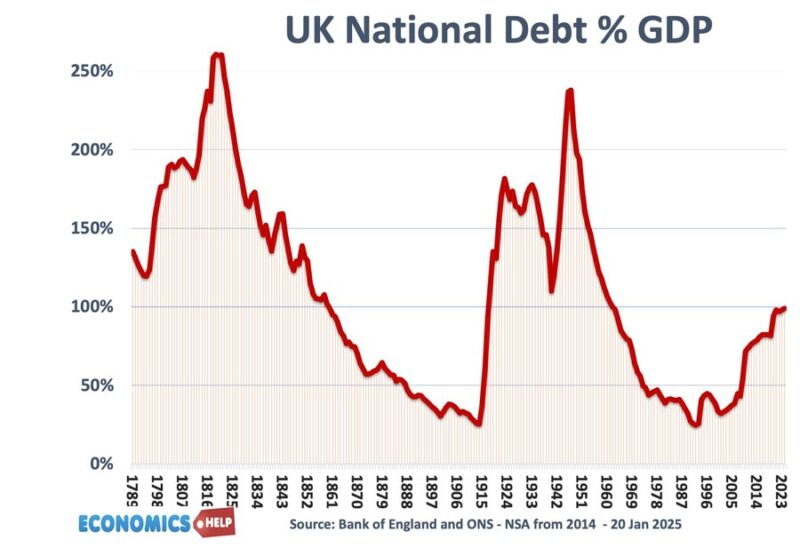
This is UK debt since 1789. It shows that it peaked during the Napoleonic War at over 250% of GDP. It reached a similar level in the early 1950s, in the aftermath of the Second World War. Yet this was not a significant problem. In the post-war period, the UK enjoyed a long period of economic expansion, where debt to GDP ratios fell. In fact, in the post-war period, the UK created a National Health Service and a welfare state. However, at the same time, there are concerns about the UK’s potential debt projection
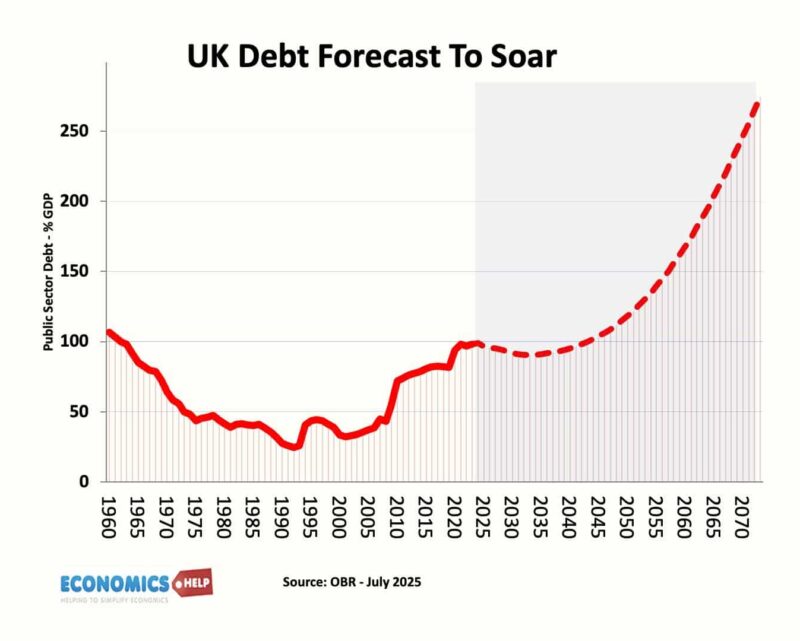
UK debt is set to soar because of an ageing population and rising welfare payments on pensions and other benefits. Also ageing population will use more health care. Will the UK be able to afford such a rise in debt?
How does the government finance its debt?

This shows who owns UK debt
- Selling government bonds to the private sector (households, insurance funds, pension funds, banks) – and overseas investors. The private sector buy bonds because the security of bonds and the guaranteed interest rate.
- The Central Bank can finance shortfall in revenue by increasing the money supply and buying bonds itself. In some circumstances, the Central Bank can create money to buy bonds – IT did this in the 2010s, which is why the Bank of England has 31% of gilts in 2023.
Factors which influence how much a government can borrow
- Cost of debt interest
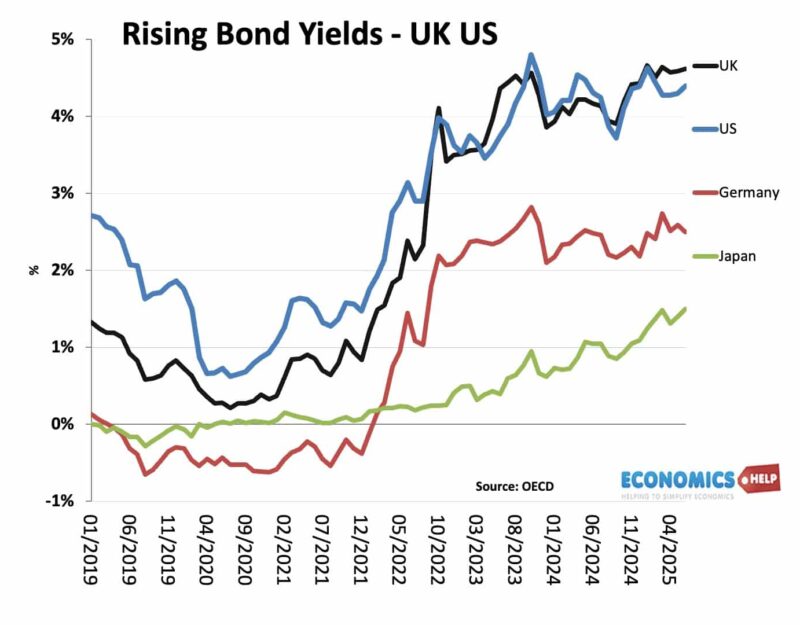
When the government borrows, it has to pay interest on this debt. If interest rates are low, then it is cheap to borrow. If interest rates rise, then it becomes more expensive to borrow. It is rising bond yields and the cost of debt interest payments that can make debt really problematic.

You can see that in 2021/22, the UK saw a big rise in debt interest payments. This was because of higher inflation, higher interest rates and so the government debt burden rose. In September 2022, Liz Truss promised to borrow an extra £100bn but, the market reacted adversely thinking this higher debt would fuel inflation, bond yields rose, and the government was forced into a u-turn. This makes debt harder to take on.

This shows interest payments as a share of revenue. Sri Lanka was facing a crisis in 2023 because of economic recession, devaluation and inflation. It led to an IMF bailout because clearly spending 79% of tax revenue on interest payments is unsustainable. The UK is spending 9.1% of revenue (aprox 4% of GDP)
- Domestic savings. If consumers have a high savings ratio, there will be a greater ability for the private sector to buy bonds. Japan has very high levels of public sector debt, but with high domestic savings, there has been a willingness by the private sector to buy the government debt. Similarly, during the Second World War, the government was able to tap into the high levels of domestic savings to finance UK debt.

This shows that the rise in government borrowing in the 2009/10 recession mirrored the rise in private sector savings. It is the same in 2020; the government borrowed more, but the private sector saved more.
A good question is, why is Japan able to borrow so much? Japan can borrow so much because the government borrows from domestic savers. Also, the government has external investment funds which give income. Therefore, the net financial liabilities are less than the gross figure. See more on Japanese debt
Borrowing in a recession
- In a depression, we tend to see a rise in private sector saving (the paradox of thrift) because households fear being made unemployed and firms don’t want to invest. Therefore, in a recession, there is often surplus private sector savings. A surplus of unused savings means there is an advantage for the government to borrow, invest, create jobs and make use of these surplus savings. As Greg Mankiw said in March 2020. “There are times to worry about the growing government debt. This is not one of them.”
- Relative interest rates. If government bonds pay a relatively high-interest rate compared to other investments, then ceteris paribus, it should be easier for the government to borrow. Sometimes, the government can borrow large amounts, even with low-interest rates, because government bonds are seen as more attractive than other investments. (e.g. in a recession government bonds are often preferred to buying shares (which are more vulnerable in a recession). This is why US bond yields fell 2008-11, despite growth in US government borrowing.
- Lender of last resort. If a country has a Central Bank willing to buy bonds in case of liquidity shortages, investors are less likely to fear a liquidity shortage. If there is no lender of last resort (e.g. in the Euro during 2011/12) then markets have a greater fear of liquidity shortages and so are more reluctant to buy bonds.
- Governments have the ability to create money. Some economists (especially those believing in MMT) argue that the only constraint to government borrowing is inflation. In other words, higher government spending financed by printing money is only a problem when it causes inflation. In a severely depressed economy, with inflation falling (and possibly deflation) it may be desirable for the government to create money and target a positive inflation rate. In 2009/10 recession, US and UK financed some borrowing through quantitative easing.
- Confidence and security. Usually, governments are seen as a safe investment. Many governments like the UK and US have never defaulted on debt payments so people are willing to buy bonds because at least they are safe. However, if investors feel a government is too stretched and could default, then it will be more difficult to borrow. Therefore, some countries like Argentina with bad credit histories would find it more difficult to borrow more. Political uncertainty can make investors more concerned.
- Foreign Purchase. A country like the US attracts substantial foreign buyers for its debt (Japan, China, UK). This foreign demand makes it easier for the government to borrow. However, if investors feared a country could experience inflation and a rapid devaluation, foreigners would not want to hold securities in that country, and it could lead to capital withdrawal. The UK is increasingly relying on foreign buyers of UK debt.
- Inflation. Financing the debt by increasing the money supply is risky because of the inflationary effect. Inflation reduces the real value of the government debt, but, that means people will be less willing to hold government bonds. Inflation will require higher interest rates to attract people to keep bonds. In theory, the government can print money to reduce the real value of debt, but existing savers will lose out. If the government creates inflation, it will be more difficult to attract savings in the future. A crucial factor is whether inflation is likely. In a recession, inflationary pressures vanish so it is much easier to finance a deficit by borrowing.
If you look at countries which have defaulted, usually inflation exacerbates the problem
Countries which have defaulted
- Argentina – Defaulted 9 times (most recently 2020)
- Venezuela – Defaulted in 2017, ongoing restructuring
- Ecuador – Multiple defaults (latest 2020)
- Brazil – Several defaults in the 19th–20th centuries
Advanced / Developed Economies
- Greece – Partial default 2012 (largest in history)
- Russia – 1998 (domestic debt), 2022 (foreign debt)
- Germany – 1953 debt restructuring (London Debt Agreement)
- Spain – Multiple defaults in the 19th century
- Sri Lanka – 2022
- Pakistan – Several restructurings
- Indonesia – 1998 Asian Financial Crisis
Countries That Have Never Defaulted
- United States (though close calls and inflation erosion)
- United Kingdom (high inflation in 1970s, caused some loss of real value)
- Canada
- Australia
- Japan
What could cause the US to default?
- Politicians take control of Federal Reserve – create money to fund debt, cause inflation and loss of confidence in US treasury bills.
- Political dysfunction – Inability to raise taxes or cut spending or agree on raising debt ceiling.
- Fall in economic growth – financial crisis
- Ageing population
Why did Eurozone countries experience more debt problems than UK and US in 2012?
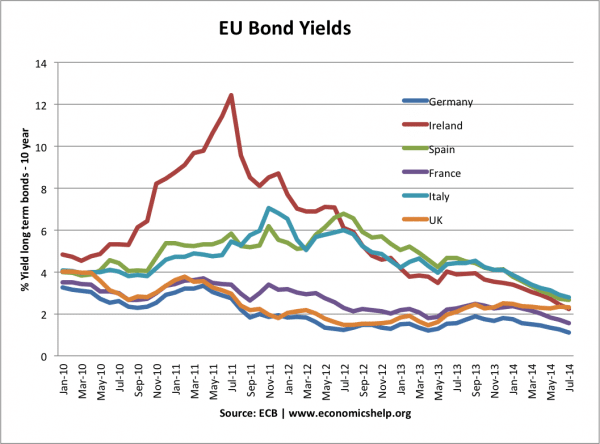
Bond yields in Italy, increased despite Italy having a primary budget surplus. This was a similar story for other countries in the Euro. One issue is that (between 2011 and 2013) Italy had no Central bank willing to act as a lender of last resort. See more reasons for Italian Debt Crisis However, when the ECB agreed to effectively intervene in the bond market, bond yields fell.
Related topics
About The Author
