
Fisher Effect
The Fisher Effect states that changes in inflation
lead to equal changes in the nominal interest rate,
leaving the real interest rate unchanged in the long run.
Nominal interest rate ≈ Real interest rate + Expected inflation
• Savers demand higher returns
• Nominal interest rates increase
• Purchasing power is protected
• Lower inflation expectations
• Nominal interest rates fall
• Real rate stays stable
Real interest rate = 2%
Expected inflation = 3%→ Nominal interest rate ≈ 5%
The Fisher effect examines the link between the inflation rate, nominal interest rates and real interest rates.
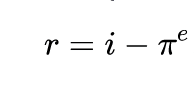
It starts with the awareness real interest rate = nominal interest rate – expected inflation.
The Fisher effect states that the nominal interest rate tends to adjust one-for-one with expected inflation, so the real interest rate stays broadly stable in the long run.
- Savers want to preserve purchasing power. If inflation is expected to rise, they demand higher nominal rates.
- Borrowers are willing to pay higher nominal rates if inflation erodes the real value of repayments.
- Competitive financial markets push nominal rates up (or down) to reflect expected inflation, leaving the real return roughly unchanged.
The link between inflation and nominal interest rates
One implication of the Fisher effect is that nominal interest rates tend to mirror inflation, making monetary policy neutral.
- If you put money in a bank and receive a nominal interest rate of 6%, but expected inflation is 4%, then the real purchasing power of your savings is rising by 2%.. Real interest rates (6-4) = 2%
- But, if the Central Bank increased money supply and the expected inflation rose from 4% to 7%, then to maintain a stable economy, the Central Bank would raise interest rates from 6% to 9%. Real interest rates (9-7) = 2%
If nominal interest rates increase at the same rate as inflation the real net effect has little impact.
Limitations of the Fisher Effect
- Elasticity of demand to interest rates. In periods of confidence and rising asset prices, high real interest rates may be ineffective in reducing demand. Therefore, in some circumstances, Central Banks may need to increase the real interest rate to have an effect.
- Liquidity Trap. In periods of stagnant growth, central Banks may cut interest rates below inflation, in order to try and stimulate economic activity.
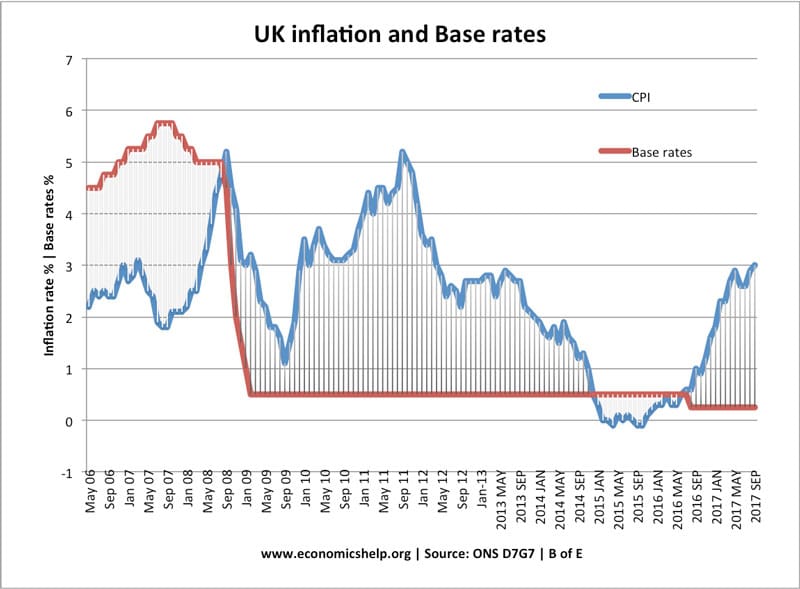 Breakdown between inflation and nominal interest rates. Up to 2008 real interest rates positive +2%. After 2009, real interest rates become negative.
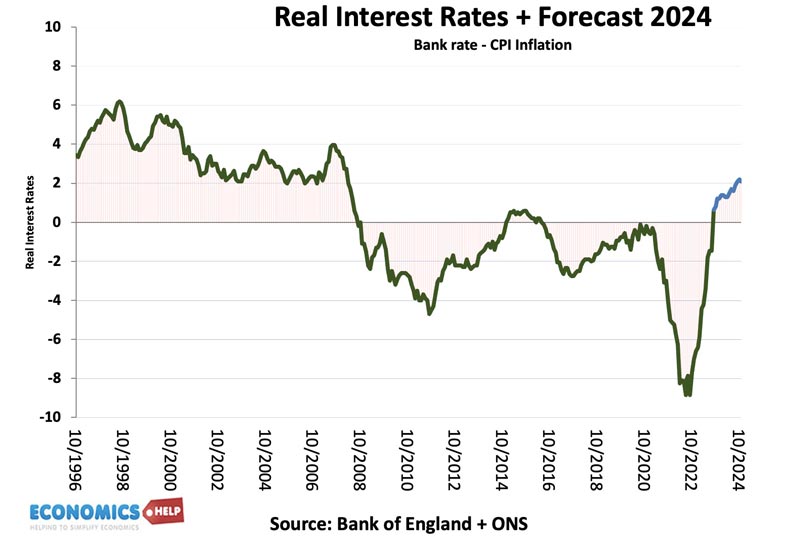
This is the real interest rate in the UK. It was positive 1996-2008. But, after financial crisis, it was largely negative.
- Too much saving. The Fischer effect states if savers expect inflation, they can demand higher interest rates, but if there is a savings glut, then interest rates may not rise because the supply of saving is too great.
- Breakdown between base rates and actual bank rates. In some circumstances, there is a breakdown between base rates set by Central Bank and the actual interest rate set by banks. This happened after the credit crunch, when Central Banks cut base rates to zero, but commerical banks were short of liquidity so kept high bank rates.
US evidence on Fisher Effect
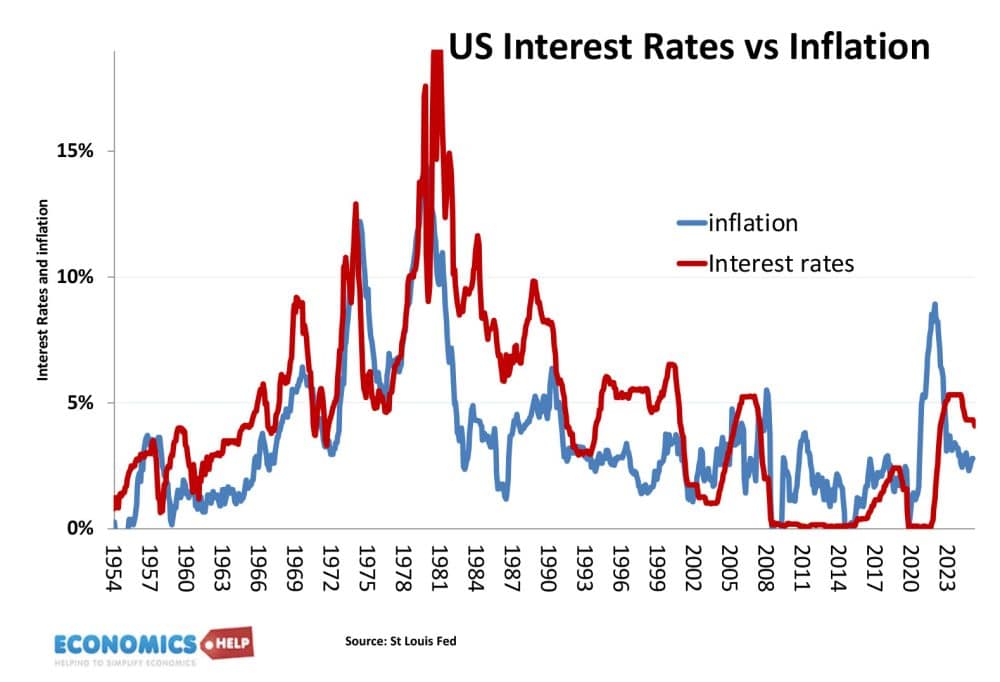
Until 2008, real interest rates largely positive, after 2008, largely negative

Fisher Effect on Bond markets and long-term Yields
For a long time, Japan had virtually zero interest rates because of deflationary pressures. However, around 2022, inflation returned,
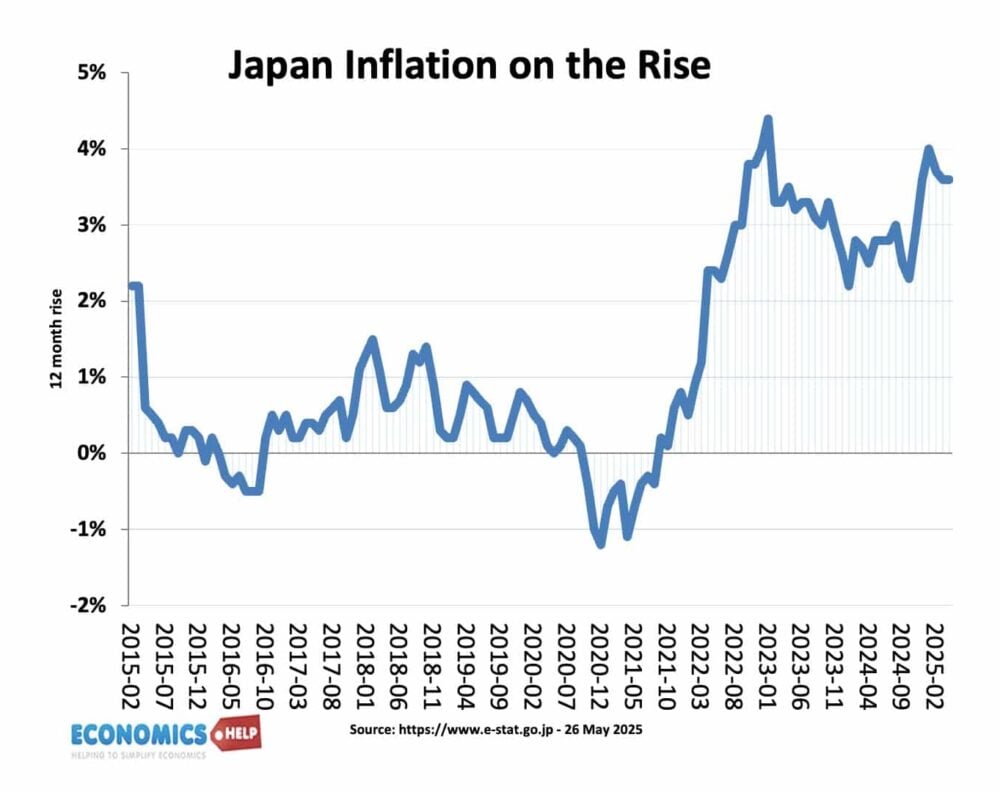
This rise in inflation, led to higher inflation expectations. It meant that market interest rates on long-term Japanese bonds rose rapidly (much higher than Bank of Japan base rates)

Basically, long-term yields embed inflation expectations; rising expected inflation lifts yields.
International Fisher Effect
International Fisher Effect (IFE)
Countries with higher interest rates are expected to see their
currency depreciate.
Expected % change in exchange rate ≈ Interest rate differential
• Higher expected inflation
• Currency loses purchasing power
• Currency expected to depreciate
• Lower expected inflation
• Stronger purchasing power
• Currency expected to appreciate
UK interest rate = 6%
US interest rate = 3%→ Pound expected to depreciate by ~3% against the dollar
Note: The International Fisher Effect works best in the long run.
Short-run exchange rates are affected by speculation and capital flows. (hot money)
The International Fisher Effect links interest rate differentials between two countries to expected changes in exchange rates.

The argument is that if a country has higher nominal interest rates, this will tend to cause depreciation because higher nominal rates imply that inflation is higher.
E.g. in 2025 UK interest rates higher than ECB (Europe) so you would expect Pound sterling to devalue because higher interest rates reflect higher inflation.
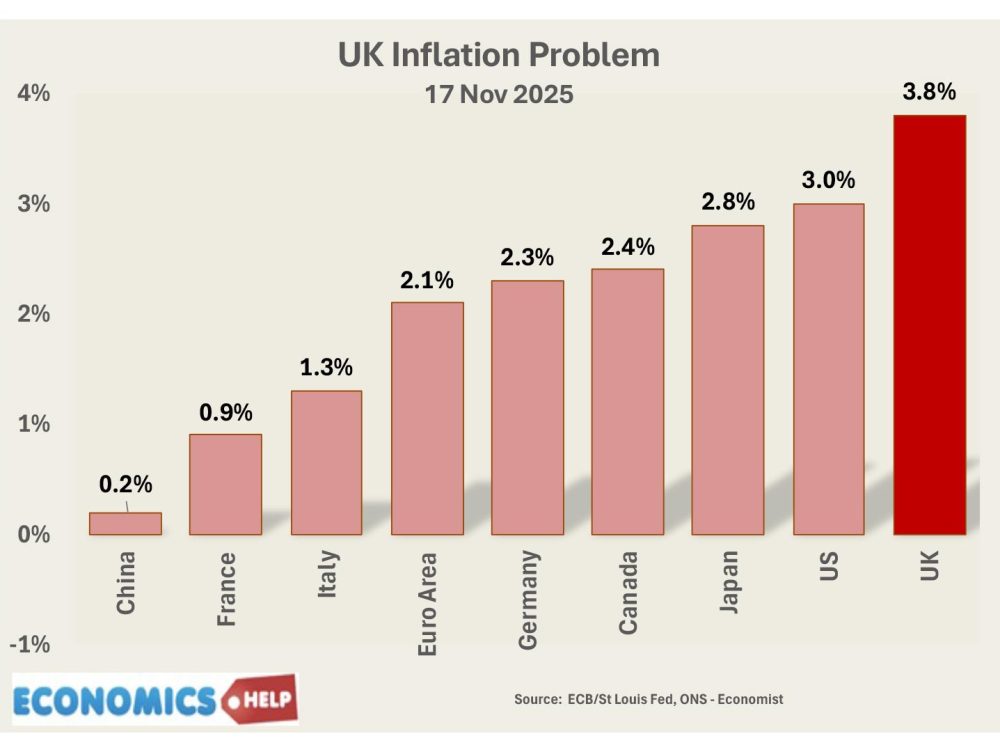
At the time, UK had higher inflation than ECB, and this will cause long-term depreciation in Pound.
Potential confusion – hot money flows
This is potentially confusing, because at least in the short-term, higher interest rates cause hot money flows and an appreciation in the exchange rate. For example, if Bank of England unexpectedly raised rates, in the short-term, this would cause more saving in UK, appreciation in sterling.
But, the Fisher effect is about long-term expectations of exchange rates. Basically, if inflation in UK is higher, then in long-term the Pound will fall against the dollar.
Related
About The Author
