A currency carry trade occurs when people borrow in one currency and invest in another country.
- For example, suppose Japanese interest rates are 0% and US interest rates are 5%.
- In this case, an investor can buy Yen and borrow from a Japanese bank at 0% interest.
- They can then exchange Yen for Dollars and put the money in a European bank, gaining 5% interest on his savings.
- Therefore, in theory, he can make a profit of 5% on the difference between Japanese and European interest rates.
Profit = (Higher foreign yield) – (Low Japanese rate) – (Any yen appreciation).
Many investors took part in this because with leverage, the potential profit is quite high. (Leverage is a way to magnify any gains, by borrowing to increase the amount you invest)

Yen Carry Trade – Explained Simply
Investors borrow yen at very low interest rates → convert to foreign currency → invest in higher-yield assets.
Borrow Yen
(low rates) e.g. 0.5%
Sell Yen
Buy USD/EM
Invest in
High Yields e.g. 4.5%
Why It Works
- Japan’s interest rates are extremely low.
- Borrow yen cheaply → invest in higher returns abroad.
- Profits rise if the yen depreciates.
Risks
- Yen strengthens → This causes losses on holding $
- High leverage means rapid forced unwinding.
- Higher Japanese interest rates can cause a short squeeze.
Problems with Yen carry trade
The only problem with the Yen Carry Trade is potential fluctuations in the exchange rates. If the US dollar depreciated, then an investor would see his profit wiped out. If the yen unexpectedly appreciates, the cost of repaying yen-denominated loans rises sharply, wiping out profits and causing rapid unwinding.
In a period of exchange rate uncertainty, it becomes less attractive to engage in any currency carry trade.

From 2019 to 2025, the Yen has been falling against the dollar, which means borrowing in Yen to buy dollar assets is even more attractive. — but also riskier in the long run.

If we zoom in on 2025, the Dollar is slightly lower at the end of the year 155 yen to $1 than at the start of the year 157 Yen to $1, which makes people nervous, the Yen could start to appreciate and dollar depreciate
Yen carry trade unwinding
To understand the impact of an unwinding Yen carry trade and its impact on the global economy, it is important to understand why the Yen carry trade occurs in the first place.
- For several years Japan has had 0% interest rates. They were much lower than other economies.
- Japan has very high levels of savings – a pool of $15,000bn. This pool of savings is worth more than the total GDP of the US economy. Japan’s excessive saving contrasts with the excessive spending and borrowing of the US.
- For a long time interest rates in Japan were low, encouraging Japanese investors to invest overseas. Why save in a Japanese bank and get 0% interest when you could save in Australia and get 6% or Europe and get 4%? Japan has accumulated $6 trillion of foreign assets. As they buy foreign assets it increases the value of foreign currencies such as the dollar
- Also many foreign investors, especially American have borrowed in Yen to invest in global stock markets. This is known as the Yen Carry Trade.
- The Yen Carry trade is profitable if currencies are stable and / or the dollar is rising against the Yen. If you borrow in Yen and then the dollar falls, you could lose despite the interest rate difference.
Rising Interest Rates in Japan
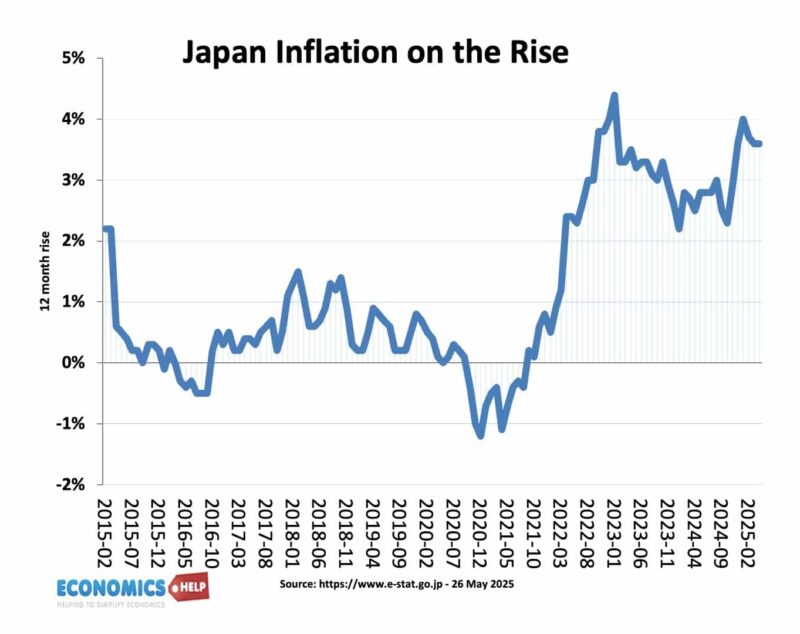
 Since 2021, interest rates in Japan have started to rise as inflation returns.
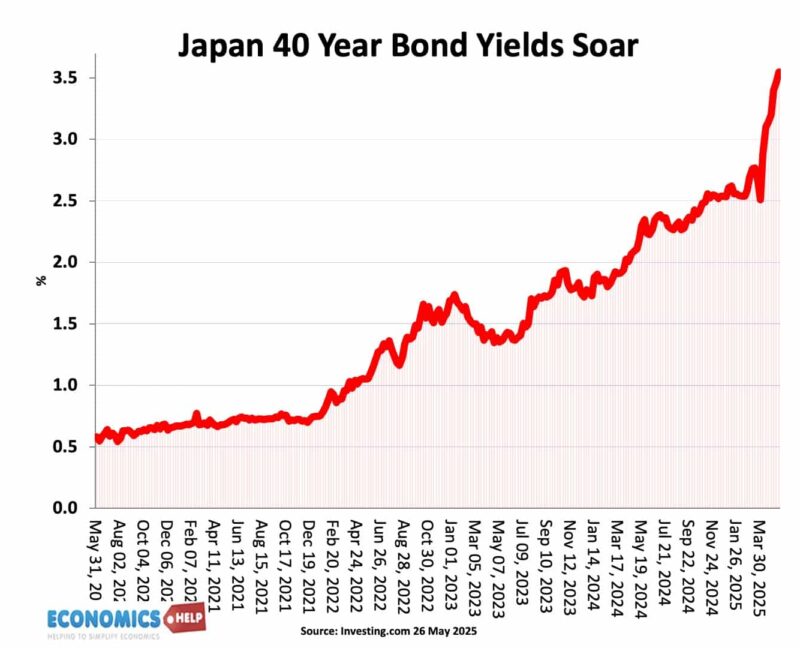
A rise in Japanese bond yields reflects concerns about size of Japanese government debt and return of inflation.
The end of the carry trade
Japan is exiting ultra-easy monetary policy
The Bank of Japan has already:
- Ended yield-curve control (targetting yield on bonds)
- Raised its policy rate above zero (first time in 17 years)
- Signalled readiness to hike again if wage growth persists
Markets now expect further tightening.. Rising Japanese yields reduce the interest-rate gap that made the carry trade so profitable.
2. Yen has been extremely undervalued
PPP and historical real effective exchange rate indicators suggest the yen has been massively cheap. If investors expect a rebound, the carry trade becomes risky because a strengthening yen wipes out returns.
IMF (Oct 2025 projection): Implied PPP conversion rate of 93.52 JPY/USD. (IMF link)
Big Mac Index (July 2025 example): Showed the Yen was 44% undervalued against the dollar (Big Mac Index) to match US Big Mac prices, suggesting undervaluatio
3. Volatility is rising
Carry trades rely on low volatility. Sharp yen swings in 2024–25 (including BOJ intervention) make leveraged positions dangerous. When volatility spikes, traders unwind positions—causing the yen to strengthen further in a self-reinforcing loop.
4. U.S. interest rates may fall
The carry trade depends not just on Japan’s rate, but on the interest-rate differential, especially with the U.S.
If:
- U.S. cuts rates (President Trump has signalled a wish to have lower US interest rates
- Japan continues to tighten …the differential narrows, reducing carry-trade returns.
5. US Dollar Weak

Expectations of falling US interest rates has reduced value of dollar
The effects of unwinding Yen carry trade
1. The Japanese have an incentive to sell their foreign investments. This means selling shares. Therefore, stock markets around the world could fall as the Japanese unwind their $6,000bn foreign holdings. (Japan is by far the world’s largest creditor nation.)
2. As the Yen rises, people will rush for the exits, selling their foreign currency to repay their Yen loans. The rise in the Yen causes a speculative bubble causing a large rise in the Yen and fall in other countries.
3. Harms Japanese exports. A higher value of the Yen makes Japanese exports more expensive reducing demand and causing lower economic growth and possibly deflation.
4. Pressure to cut Japan rates To deal with the rising Yen and slowing economy, Japan could try cut rates, but the problem is inflation is now more embedded in the economy
5. Lower value of %. An appreciating Yen will cause depreciation in other major currencies as Yen appreciates.
What will Happen Next in 2026?
In the short term: carry trade likely to some extent
Unless the Bank of Japan tightens significantly, yen funding will stay attractive because:
- Japanese interest rates are still extremely low by global standards.
- Markets expect only gradual BoJ hikes, not a rapid tightening cycle.
- The yen has already weakened, signalling room for further depreciation if policy divergence continues.
The bigger the carry trade gets, the more vulnerable it becomes. Why?
- Positions are leveraged.
- Investors believe depreciation is a “one-way bet.”
- Yen historically undervalued on PPP.
- A small yen appreciation could trigger margin calls and forced unwinding.
Scenario A — BoJ remains ultra-dovish
- Yen stays weak.
- Carry trade grows even more.
- Risk builds silently in the background.
This mirrors the 2005–2007 period.
Scenario B — BoJ signals faster tightening
Government has indicated a willingness to increase government spending, which has contributed to inflation, putting upward pressure on interest rates in Japan
- Rate hikes
- Ending yield curve control (allowing rates to rise)
- Teducing balance-sheet support Bank of Japan owns a lot of Japan debt
What could cause a Yen short Squeeze?
A yen short squeeze occurs when investors who borrowed or sold yen (to fund carry trades) are suddenly forced to buy yen back quickly, driving its value sharply higher. This appreciation in the Yen, would cause knock on effects because others would then have to unwind their positions too.
If the yen is heavily shorted, any unexpected shock could set off a big reaction. Triggers for a Yen short squeeze
- US recession → lower US yields
- US president putting pressure on Fed to lower US yields
- US inflation unexpectedly falls causing lower US yields
- Geopolitical shock → safe-haven yen demand causing Yen appreciation, making it difficult to pay off Yen loans
- Japan faces continued higher inflationary pressures – from government spending, rising food prices, loose monetary policy.
- Upward pressure on Yen from historic undervaluation.
Related pages
About The Author
