The Housing Market refers to the supply and demand for houses, usually in a particular country or region. It refers to the system through which individuals attempt to buy, sell or rent properties. It involves an interaction of landlords, tenants, banks, estate agents and is usually overseen by some government regulation.
House prices and house rents are determined by factors such as income, interest rates, population and the supply of housing.

This shows how UK house prices have risen, showing how demand for housing has risen faster than supply.
Location
A key factor is also how you define the housing market because it will vary from region to region, but also between cities and even from street to street.
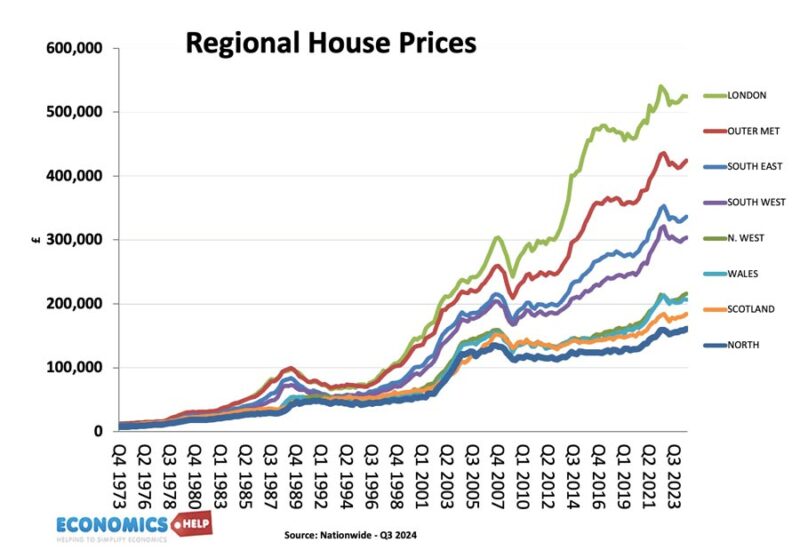
This shows regional house prices in the UK, with London averaging over £500,000, but in the north less than £160,000. But, even within London prices can vary tremendously.
- The borough of Kensington and Chelsea averages £1.263 million
- The borough of Barking and Dagenham averages £362,000.
The housing market usually has three main sub-sections
- Homeownership – buying through a mortgage or outright
- Private rented sector. Renting from a private landlord.
- Social renting – subsidised rent from the government.
Definitions related to the housing market
- UK nominal house prices – actually monetary value – not adjusted for inflation
- Real house prices – house prices adjusted for inflation, e.g. if prices rise 10%, but inflation was 2%, then real house prices rose 8%

- Mortgage equity withdrawal – when homeowners re-mortgage house and take equity withdrawal.
- Affordability index – how much percentage of disposable income is needed to keep up with mortgage payments – and rents.
- Buy to let – When investors buy houses with the intention of renting out the house to gain income from rent and hopefully capital gains.
- Capital gains – when investors see a rise in house prices
- Negative equity – when a homeowner has an outstanding mortgage bigger than the value of the home. If they sold their house, they would still owe money from the initial mortgage
- Real interest rates – nominal base rates – inflation rate
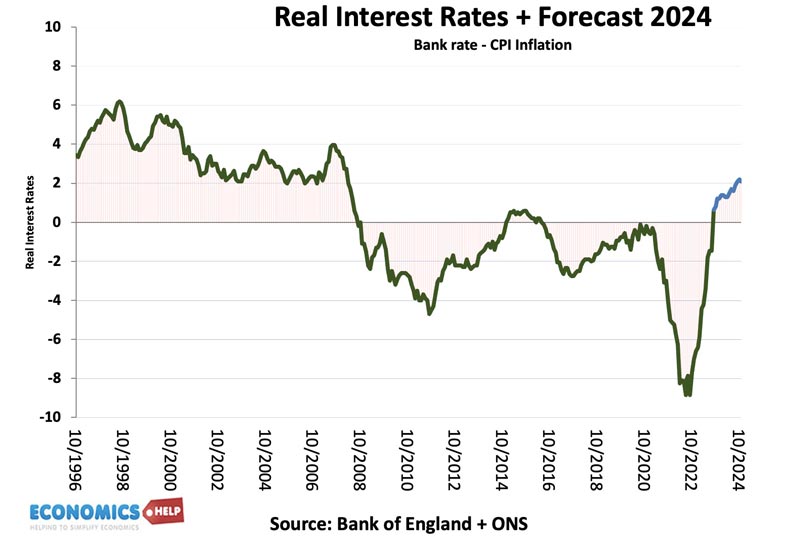
- Base rates – the interest rate set by the Bank of England; this base rate has a strong influence on the other interest rates in the economy. Banks will usually alter their lending rates in response to a change in the base rate.
- Fixed-rate mortgage – a mortgage where the interest rate is set for a number of years e.g. 2,5,10 years
- Variable-rate mortgage – a mortgage where the interest rate is linked to the Bank of England base rate and so mortgage payments will change with changes in the interest rate.
- Interest-only mortgage – when homeowners take out a mortgage which only involves paying the interest on the loan and not any principle on reducing the outstanding loan.
- Generation rent – the young population who cannot afford to buy, but have to rent.
Real house prices 1975 – 2021
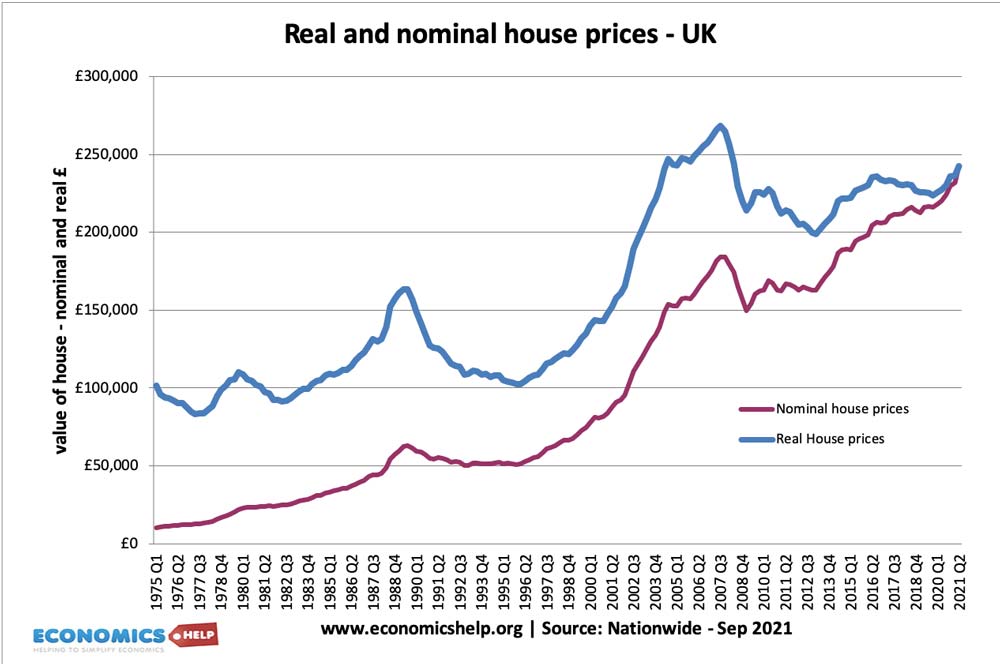
A comparison between real house prices and nominal house prices.
The Housing Market includes the following features
- Supply of housing – quantity of housing stock
- Demand for housing
- House prices
- Rented sector. Buy to let investment and demand from tenants
- Government intervention in the Housing market
Factors which affect the Housing Market
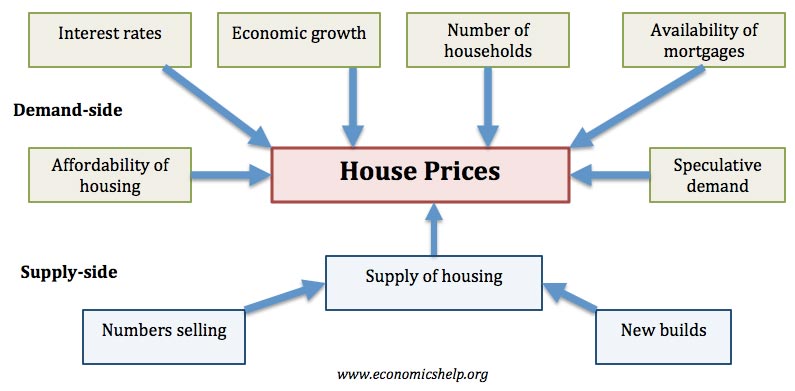
- Interest rates – which influence cost of variable mortgages
- State of mortgage industry – determines whether people are eligible for mortgages
- Economic growth, incomes and unemployment rates
- Population and demographic trends.
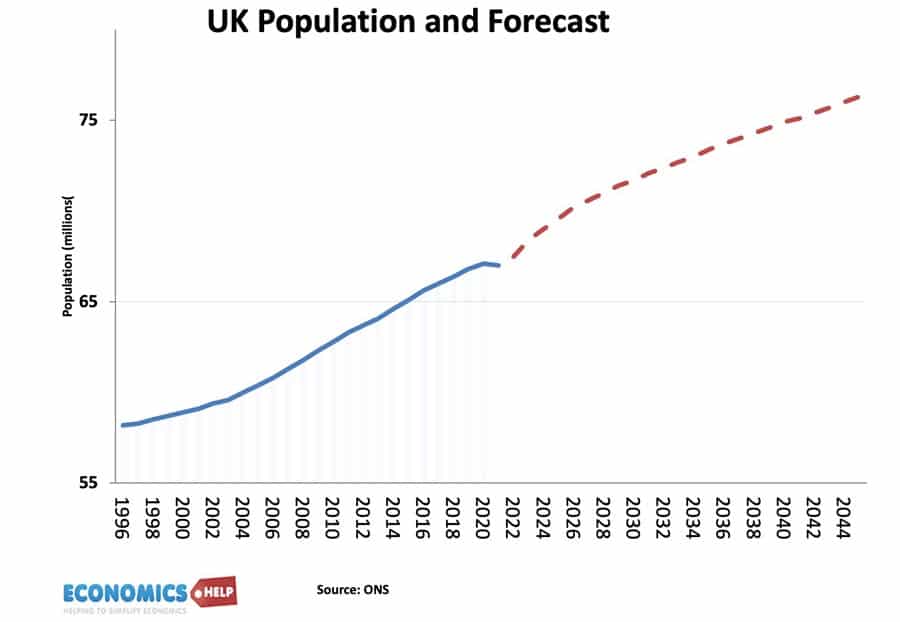
The growth in the UK population has important implications for the housing market, because it is a derived demand. Derived from the number of individuals and households.
Features of UK Housing Market
- The UK Housing Market is often volatile because of various factors.
- The UK Housing market has an influence on the wider economy. e.g. when house prices are falling, consumer spending tends to decrease.
- Because the housing market influences the economy and individual homeowners, it is important to try and be able to predict future movements in the housing market.
Homeownership rates
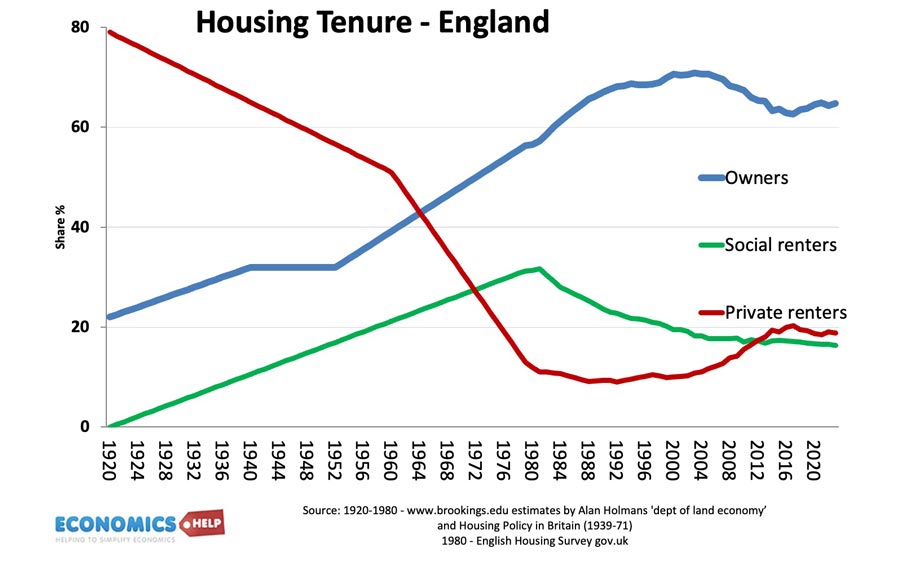
In the UK, there was a rise in homeownership from 1920 to 2004. But, has since started to go into decline because of declining affordability. Social renting rose from 1920 to 1980, but also gone into decline, leaving the private rented sector to grow in size.
The main forms of housing tenure are
- Homeownership – either outright or through mortgage
- Private renters – renting from private landlords
- Social renters – people renting from local authorities and housing associations.
Government regulation of the housing market
- Tax – Stamp Duty levied on buying houses above a certain level.
- Planning laws – affect how much supply will increase
- Laws about over-crowding and minimum standards of insulation
Supply of Housing
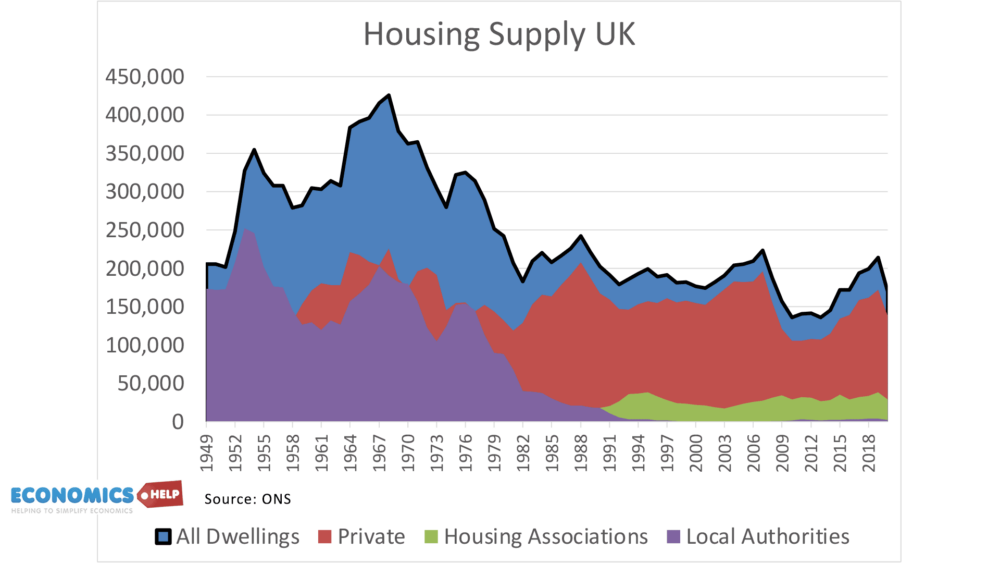
This shows the housing supply in the UK, the number of new houses built has declined since the 1960s.
House Price Inflation

This shows house price inflation in the UK, when the market is booming, with strong demand, house prices are rising. There are three periods of falling house prices.
- Early 1990s in response to interest rates rising to over 12% (and recession)
- 2008/09 – Credit crunch caused a drop in supply of mortgages
- 2023/24 – Response to rise in interest rates post-covide
Affordability of housing

One measure of affordability is the percentage of take-home page that goes on a mortgage/ renting. This shows in the late 1990s housing affordability declined due to higher interest rates.
Related
About The Author
