The hypothesis of financial instability was developed by the economist Hyman Minksy. He argued that financial crisis are endemic in capitalism because periods of economic prosperity encouraged borrowers and lender to be progressively reckless. This excess optimism creates financial bubbles and the later busts. Therefore, capitalism is prone to move from periods of financial stability to instability. This is a type of market failure and needs government regulation.
Financial Instability could be summed up as:
Success breeds excess which leads to crisis
Or
Economic stability itself breads instability.
Since the credit crisis, many have looked back at the Great Moderation (a prolonged period of economic growth during the 1990s and 2000s) had examined how it contributed to complacency and risk-taking.
Minsky’s Financial Instability Hypothesis
The Financial Instability Hypothesis (Hyman Minsky) argues that long periods of economic stability encourage risk-taking, which eventually makes the financial system unstable.
1. Hedge Finance
Borrowers can repay both interest and principal from current income.
Risk is low and lending standards are cautious.
2. Speculative Finance
Borrowers can repay interest only and must roll over debt.
Asset prices rise and leverage increases.
3. Ponzi Finance
Borrowers cannot repay interest without further borrowing.
Debt depends entirely on rising asset prices.
Financial Crisis
When asset prices stop rising or interest rates increase, confidence collapses. Forced selling causes asset prices to fall, triggering recession.
Housing bubbles, leveraged asset markets, and speculative investment in new technologies (e.g. AI).
Stability is destabilising — periods of calm encourage behaviour that eventually leads to crisis.
How economies go from stability to instability
- Traditionally, bank lending is secured against assets. The lending is hedged against default. For example, banks lend mortgages if people can raise a deposit and can maintain mortgage payments to repay both the capital and interest. Typically banks would also check strict lending criteria to make sure the mortgage is affordable.
- However, if house prices rise and there is economic growth, both lenders are borrowers become more optimistic and willing to take on greater risks.
- Banks insist on smaller deposits and are willing to lend bigger multiples of income.
- Lending becomes more leveraged.
- The greater lending itself causes asset prices to rise and this increases confidence even further. People keep expecting rising prices – the past becomes the guide to the future.
- We could term these sentiments as ‘Irrational exuberance‘ There is a feeling that the crowd can’t be wrong. If everyone expects asset prices to keep rising, it’s easy to jump on the bandwagon.
- Rather than hedge borrowing (safe secured lending) we see a growth of speculative lending and even ‘Ponzi borrowing’. This means banks and financial institutions lend money in the hope that asset prices keep rising to enable repayment. However, the loans of a Ponzi nature are unsustainable in the long term.
- Regulatory capture. Regulators who should be insisting on safe lending levels also get caught up in the irrational exuberance. Credit rating agencies make mistakes in allowing speculative and Ponzi borrowing.
- However, this asset bubble and speculative lending cannot be maintained forever. It is based on the unreasonable expectation that asset prices keep rising beyond their real value. When asset prices stop rising, borrowers and lenders realise their position has left them short – they don’t have enough cash to meet their repayments. Everyone tries to liquidate their assets to meet their borrowing requirements. This leads to a loss of confidence and credit crunch.
Minksy Moment
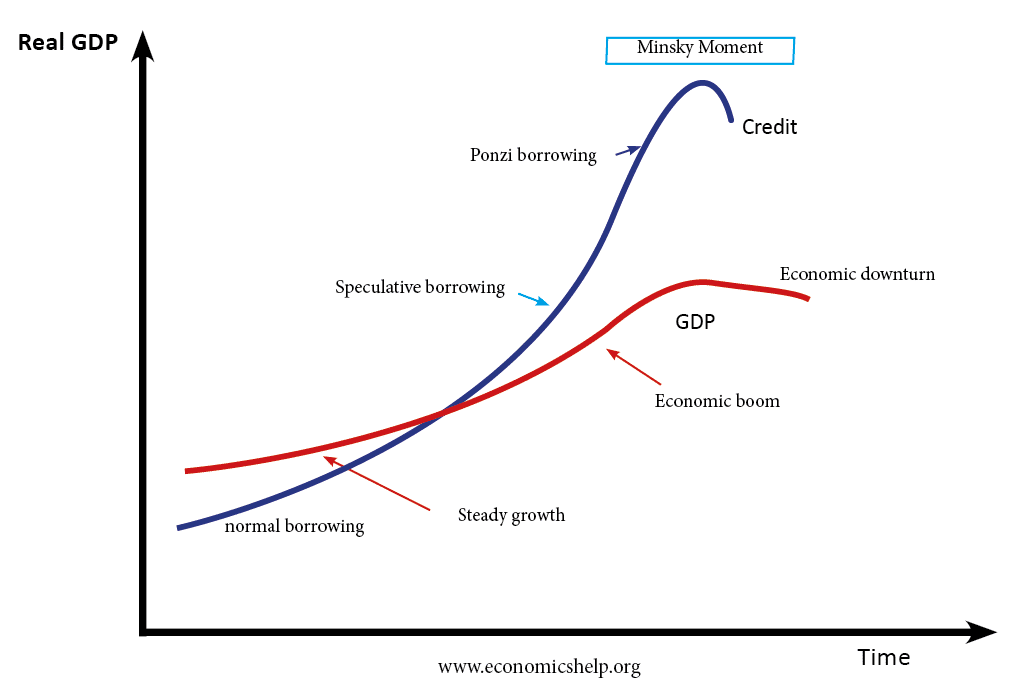
The Minsky moment refers to the point where the financial system moves from stability to instability. It is that point where over-indebted borrowers start to sell off their assets to meet other repayment demands. This causes a fall in asset prices and a loss of confidence. It can cause financial institutions to become illiquid – they can’t meet the demand for cash. It may cause a run on the banks as people seek to withdraw their money. Usually, the Minksy moment comes when lending and debt levels have built up to unsustainable levels. It can lead to a balance sheet recession
Implications of Financial Instability Hypothesis
Minsky argued that because capitalism was prone to this instability, it was necessary to use government regulation to prevent financial bubbles. This financial regulation could include:
- Regulation to prevent speculative and Ponzi lending.
- Requirements banks keep a certain liquidity in cash reserves.
- Requiring banks to contribute to a stability fund during boom years, which is to be used in times of crisis.
- Strict requirements for mortgage lending, i.e. not allowing self-certification mortgages, interest-only mortgages e.t.c.
- Willingness to act on asset price inflation, e.g. raising interest rates if there is excess house price inflation.
- Splitting up banks between traditional saving divisions and more risky investment banking.
- A strong Central Bank willing to act as lender of last resort.
Financial Instability and Credit Crunch
The work of Hyman Minsky was largely ignored by mainstream economics in the 1970s and 1980s. Instead, there was widespread support for financial deregulation. But, the credit crisis of 2007 onwards understandably created renewed interest in his work. The model seemed to offer a considerable explanation for elements of the credit crisis.
- The movement from hedge lending to speculative and Ponzi lending, best exemplified by the sub-prime mortgage lending in America
- The increase in asset prices (especially house prices) is above long-term price to income ratios.
- The growth of confidence in rising asset prices and continued economic growth.
- The belief we had seen the end of the boom and bust cycle.
- The failure of credit rating agencies to adequately see the risk in mortgage debt bundles.
- The willingness of commercial banks to borrow money on money markets to enable more profitable lending.
- A culture of risk-taking emerging in banks, with high rewards for rapid growth.
We could argue there was a moment between 2003-2004, where mortgage lending and house prices became unsustainable. However, it took a few more years for the financial bubble to burst with devastating consequences. ‘The Minksy Moment’
Financial Instability and AI Bubble?
Rapid advances in AI have led to surging valuations in tech firms, especially those linked to chips, data centres and AI platforms. Expectations of future profits may be over-optimistic, pushing share prices beyond fundamentals.
This mirrors earlier episodes such as:
- the dot-com bubble (late 1990s)
- the railway mania (1840s UK)
If profits fail to materialise, a sudden fall in prices could trigger negative wealth effects and reduced investment

The Case-Shiller index measures price of shares to earning ratios. It shows the dot com bubble and bust in 2001, it also shows the growth in valuations in 2024/25. These growing PE ratios are being driven by the big seven tech stocks. The market is become subject to intense speculation
Investors may buy AI-related assets not because of fundamentals, but because others are buying. This Some AI investment is financed through cheap credit and venture capital rather than current profits.can detach prices from underlying productivity gains. Some AI investment is financed through cheap credit and venture capital rather than current profits.
Circular nature of AI. AI has something ofa self-reinforcing investment loop
Rising AI share prices → Cheaper equity finance for AI firms → More spending on chips, data centres and models → More impressive AI capabilities and hype → Further rises in valuations
- NVIDIA sells GPUs to: Microsoft (Azure) for OpenAI Google for Gemini Amazon (AWS) for Anthropic
- These firms then use AI models to sell cloud services, generating revenue that is reinvested in more NVIDIA chips.
- TSMC manufactures NVIDIA’s chips, funded indirectly by this AI demand cycle.
However, AI may not be bubble
- Unlike many speculative assets, AI could deliver real efficiency gains across healthcare, finance, logistics and education. If productivity rises, higher valuations may be justified.
- The AI boom is largely driven by equity markets, not household borrowing. This makes it less likely to trigger a banking crisis or deep recession.
- The Big Tech firms are financing investment out of current profits, not borrowing
Limitations of Financial Instability Hypothesis
- Government regulation of financial markets is often more difficult in practice than theory. Financial firms have ways of avoiding government regulation.
- Regulators may fail because they get caught in same ‘irrational exuberance’
- Financial instability is not the only cause of the 2008 crisis. For example, we had a prolonged growth in total debt levels, there was evidence of global imbalances, with large current account deficits in US, UK and Europe.
Related
About The Author

2 thoughts on “Financial Instability Hypothesis”