
UK House Price to Income Ratio and Affordability

house-price-to-earnings-ratio

An examination of UK house price affordability. Latest data

hpe-nationwide-20250q4


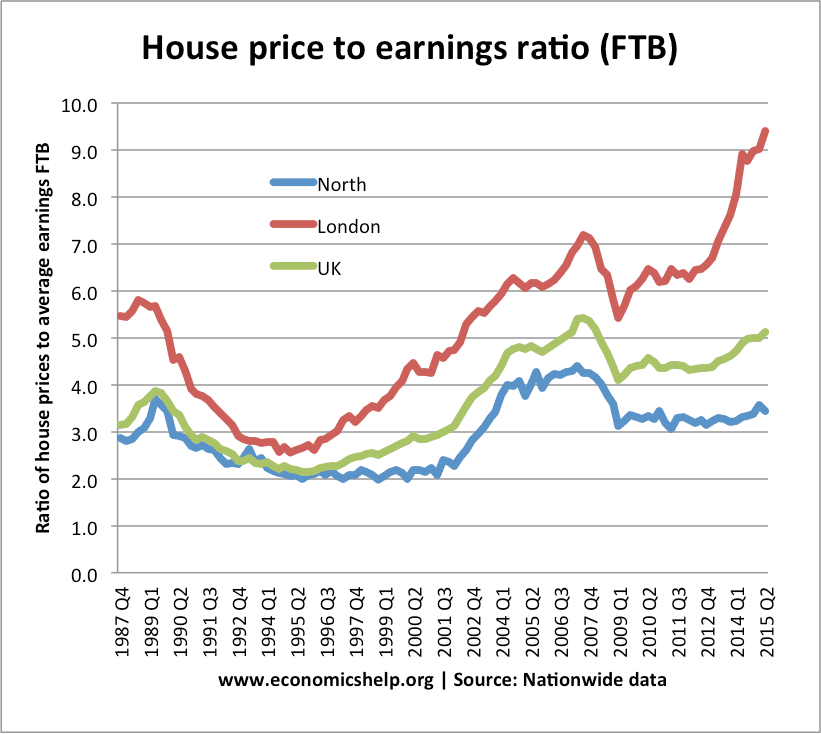
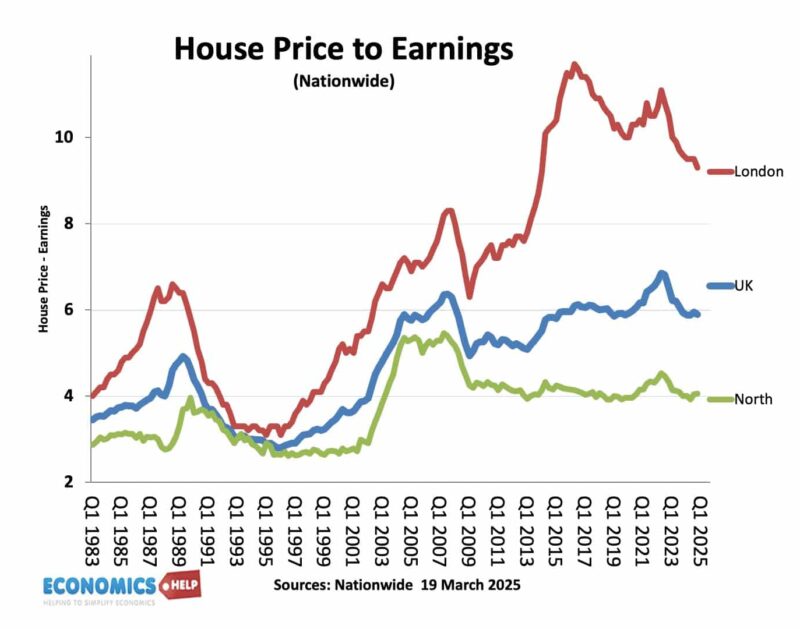
UK House price to earnings ratios  (all buyers) reached a peak in 2022 of 7 times earnings (Nationwide data), since then affordability has improved somewhat, but still out of reach for many potential first time buyers.
house-price-earnings-uk-london-north


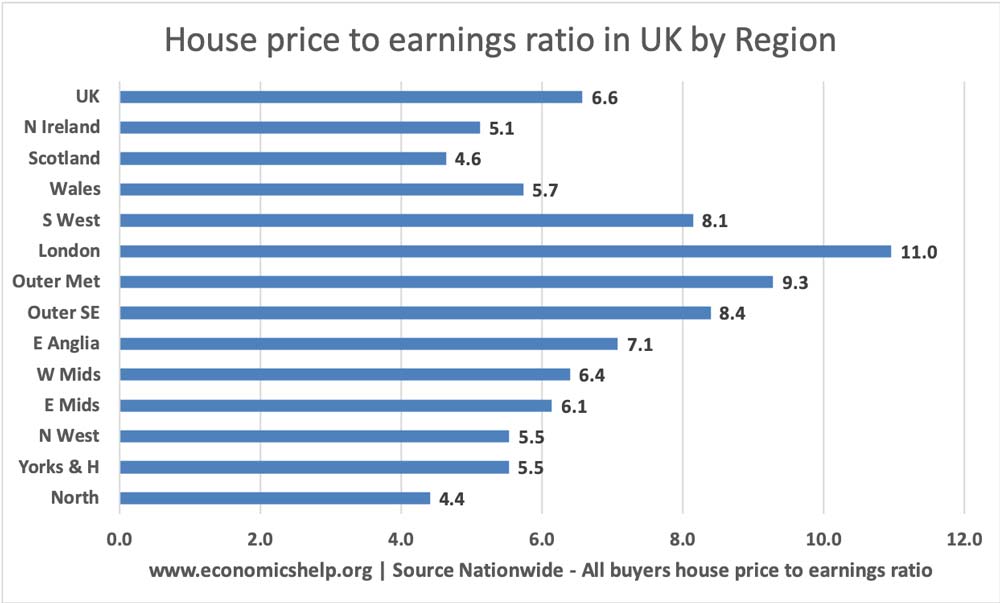
The house price to earnings ratio is most extreme in London, with the ratio reaching 9.5 times salary. Housing prices in the North, Scotland and Northern Ireland are relatively cheap in comparison.

In many parts of the country, potential buyers are being kept out of the market due to house prices being much higher than average incomes. For young people especially, owning a home has become increasingly unrealistic because the deposit required is out of reach for most workers.

Regional House prices
house-price-earnings-ratio-uk-regions-2021

UK real house prices since 1975

real-house-prices-falling-mar-26

This shows average house prices – adjusted for inflation. It shows that between 1996 to 2008, house prices rose considerably faster than the average price level. However, since 2008, real house prices have fallen 20% in real terms. Yet, despite falling in real terms, affordability has not improved as much as you might expect because of stagnant average incomes

Mortgage payments as % of income

One useful measure of housing affordability is to look at mortgage payments as a percentage of income.

For first time buyers taking on large mortgages, the mortgage payments are still taking up a big % of take-home pay – despite the low-interest rates. The average mortgage payments are lower for average homeowners because many householders took out a mortgage when house prices were cheaper. In this regard, it doesn’t look too bad.

mortgage-payments-share-income

Since interest rates were cut in 2009, mortgage holders have benefitted from low-interest rates, which have made mortgage payments cheaper.

  • However, when interest rates rose in 2022 many homeowners saw a nasty shock of rapidly rising mortgage payments.
  • Also, rising house prices have required a bigger deposit. This means many who might be able to afford mortgage payments are unable to get a mortgage in the first place

mortgage-rates-fixed-dec-25

Mortgage rates have started to fall since the 2023 peak. But, it is still considerably higher than the 2021 lows.

Historical House Price Affordability
historical-schroder-house-price-income-1920

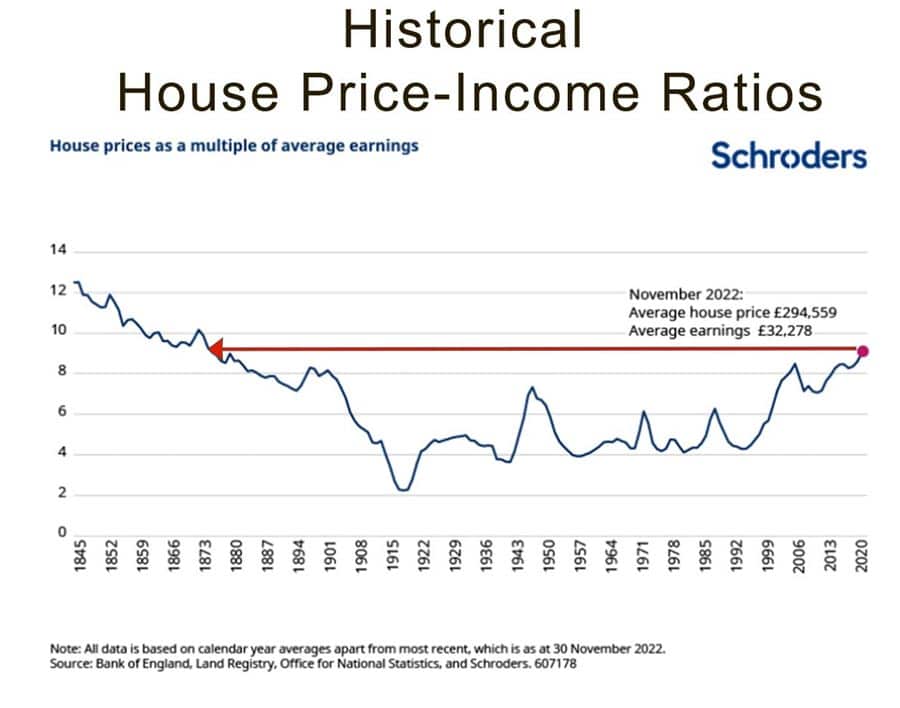
Going back to the Victorian Age, house prices were over 12 times income. This ratio fell due to the growing supply of houses as towns were expanded into the suburbs. A big factor was the growth of railway, which enabled people to live further from work. It also made it cheaper to buy. Since the early 1990s, there has been a new increase in relative cost. Partly due to increased wealth effect.

ONS measure of affordability

hpe-ons-long-term

House price affordability since the 1960s. The ONS measure state house prices to incomes are roughly 7.6 times average incomes. It is lower than 2022 peak, but still higher than the pre-crisis 2008 credit crunch.

house-prices-faster-than-incomes


  • House prices have risen significantly faster than average earnings. This is one factor in explaining why the average incomes of those with a mortgage have more than doubled in recent years.
Read more

Policies to ease pressure on the housing market

Readers Question: What policies could be used to ease pressure on housing market?

Firstly, the main pressure in the UK housing market is the persistent and continued above inflation price increases. Back in 2004, Kate Barker’s report into housing market trends found that the UK would need to build 250,000 houses to reduce the house price inflation rate to 1.1%. But, since 2004, the UK housing market has fallen short of this target. In the middle of the recession, the number of home starts fell to just over 100,000. (Housing supply)

The  Home Builders Federation claim to catch up, we would need to increase home building to 320,000  a year – something not seen in the UK since the 1950s.

Policies to ease pressure on housing market

1. New Garden cities The building of new cities, in the mode of Milton Keynes, can enable a significant increase in homes. Currently there are plans for a new city in Ebbsfleet, Kent on the high speed railway line to London.

However, from planning to completion this will take a long time. It also means building on greenbelt land, which is likely to raise objections.

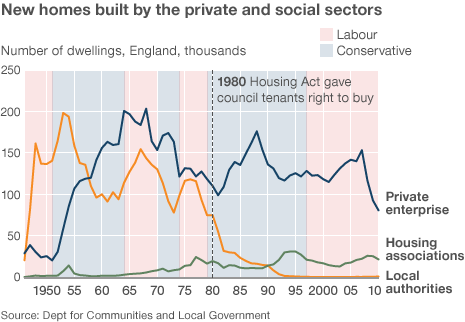
2. Government subsidy / council homes. Additional government spending to subsidise the building of ‘social’ housing could help increase supply. In the past decades, council housing has fallen out of vogue as the government have sought to sell off council housing and cut back on the building of council housing. But, it was council houses which provided a significant boost to the UK’s housing stock in the post war period.

housebuilding_464

Clement Attlee’s post-war Labour government built more than a million homes, 80% of which were council houses. In recent years, local authority building of new houses has virtually ceased. It is notable that since local authorities ceased to build homes, the UK housing shortage has become more acute. Housing associations have never been able to replace the large numbers built by local authorities.

It would require a change in political commitment and the willingness to spend extra money. Also, since the Thatcher era, the notion of council housing has gained a form of social stigma. However, it could make a big difference to the number of homes built.

3. Greater flexibility in planning. Planning restrictions are quite strict in the UK. Loosening the number of restrictions and making it easier for builders will make supply more elastic. This could involve reducing the amount of protected greenbelt land. It could also involve streamlining the regulations home-builders have to meet.

However, this could lead to significant local objections as people protest about the increased building, congestion and loss of green fields. One other solution would be to provide grants for turning derelict brown field sites into new homes.

4. Incentives for local authorities

Home building is a local issue. Local authorities have to deal with opposition to home building, so there is often local political pressure to stop house building. However greater financial incentives, such as allowing the council to keep council tax receipts from new housing developments, could give them a greater motivation to allow home building.

5. Introduction of a Planning-gain Supplement scheme

At the moment, building new houses tends to give the greatest benefit to landowners. Local residents feel they just lose out – depressed house prices, loss of unique village e.t.c. One solution is to make sure local residents near new housing schemes gain some compensation in return for accepting more houses. For example, a new housing development could be accompanied with a bypass or better public transport links. This is interesting from an economic perspective as it is seeking to provide a pareto improvement (one where everyone benefits).

The difficulty is that in the real world, it can be difficult to ensure people are compensated. Some local residents may feel there is nothing to compensate for the loss of a beautiful view. People may also exaggerate how much they lose from a new housing scheme.

6. Government’s Help to to buy

The government’s help to buy scheme is controversial because it is seeking to ease the problem through helping homeowners borrow more money. Critics argue this merely fuels demand and keeps prices artificially high.

However, to some extent, the Help to Buy scheme has provided some incentive for private builders to increase supply. In particular the first part of the scheme which offers buyers an interest-free loan worth up to 20% of the value of a new-build home. This increased demand for new build homes, encourages house builders because they are more confident there will be demand for the new homes.

Read more

Item added to cart.
0 items - £0.00