All the latest data on UK house prices, affordability, supply and mortgage costs. Also, what will happen to the housing market, interest rates and prices?
The consensus is for modest rises in house prices in 2026, as mortgage rates are expected to come down slightly, however, the housing market is stretched by high ratios of house price to income, which mean many are frozen out of the housing market.

A video on the prospect for the housing market in 2026.
House price inflation in UK

This shows that UK house price inflation is mostly positive, especially in the run up to the credit crunch. However, house prices don’t always go up.
When House Price Fell
- 1990-1996 (due to interest rates of 15% and recession of 1992)
- 2008-09 (due to credit crunch and banks being unable to lend
- 2023 (High levels of unaffordability and higher interest rates)
- Currently, house price inflation is relatively low and similar to the rate of inflation.
UK House prices in the past few decades
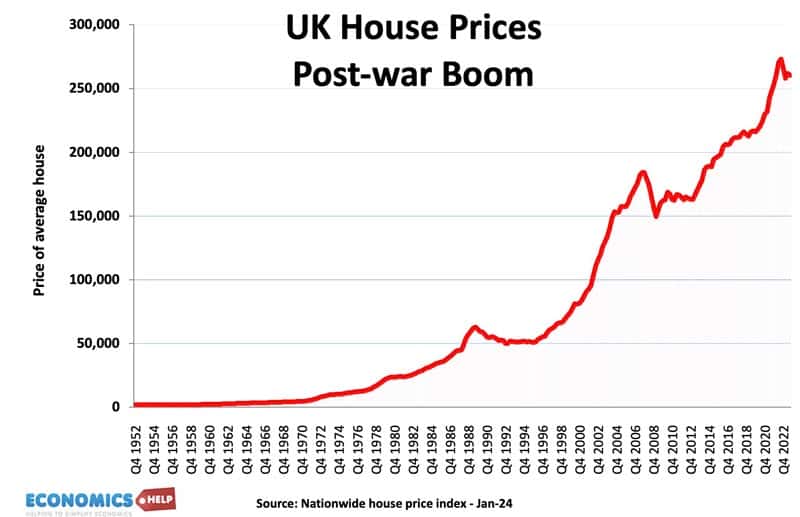
How House Prices have changed
- In 1969, average house prices were: £4,312
- In 1975, average house prices were: £10,388.
- In 1980, average house prices were: £22,676
- In 2016, average house prices – £198,564.
- In 2025, average house prices – £272,751
- See also: historical house prices since Victorian Era
Real house prices – Adjusted for inflation

Real house prices are adjusted for the effects of inflation. This gives a more meaningful guide to how house prices have increased compared to typical prices in the economy.
This shows the real increase in house prices – rising faster than inflation.
- In 1975 – average house prices (at 2025 prices) was £136,000.
- In 2025 – average house prices – £272,000
- 100% increase in real house prices.
- Of particular note is how much real house prices have fallen since 2007, this is because of the relatively high inflation rate, reducing the value of houses.
2. Affordability of Housing
ONS Measure
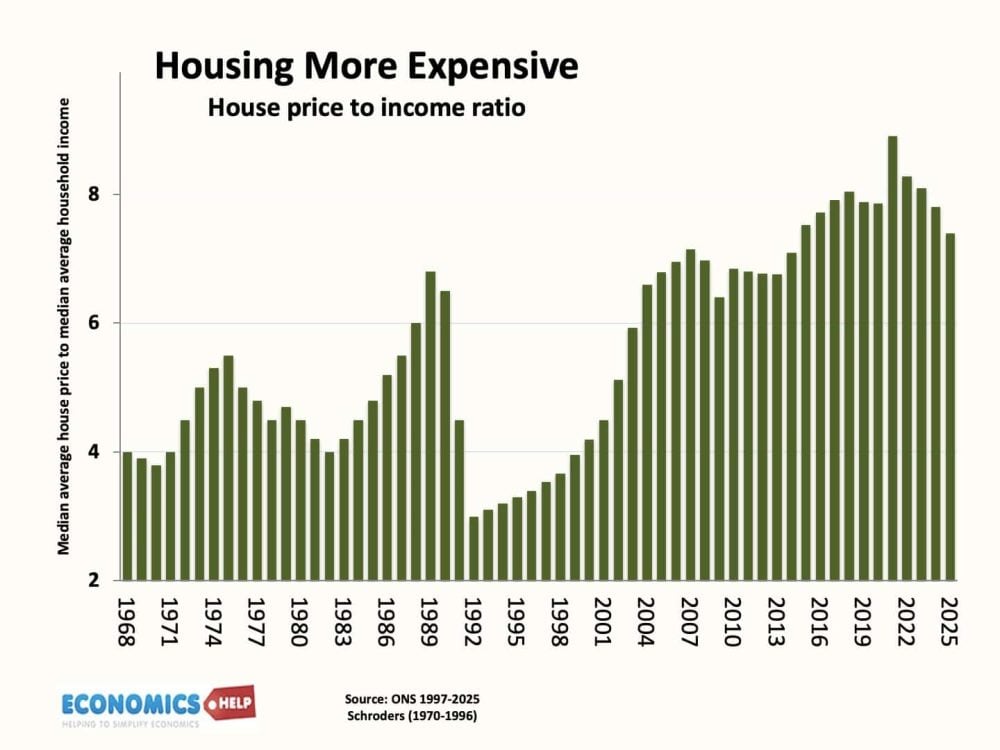
This shows how house prices reached a peak at the end of 2021 – 8.9 times median average incomes. Since then the ratios has slightly fallen, but it is still above the peaks of the late 1990s boom and 2007 bubble, indicating how historically, UK house prices are overvalued.
For UK first time buyers, the average house price is 5 times average earnings. In London, house prices are 9 times average earnings, whereas, in the north, house prices are only 3.2 times average earnings.
Affordability varies a lot by region. see more on affordability of housing
Affordability of Mortgage Payments

Mortgage payments as % of income reached a peak in late 1989/90 due to record high-interest rates. Rising house prices meant that the % of mortgage payments grew in the 2000s. However, in 2009, interest rates were cut to 0.5% leading to lower mortgage payments for homeowners.
Interest rates in the UK

interest rates at the Bank of England

Mortgage Calculator
Since the peak of interest rates in 2023, both bank rates and mortgage rates have come down. So far the Bank of England is predicting a modest cut in interest rates in 2026
Further reading: UK housing affordability
4. Housing Supply

During the post-war period, construction of local government housing increased supply. Home builds reached over 400,00 a year in the late 1960s. However, from the 1980s, the government retreated from building houses, leaving it to the private sector and a small contribution from housing associations. Due to strict planning legislation, the supply of housing has failed to meet government targets.

The government are seeking to increase house building, but it has proved more difficult than they hoped.
Understanding supply constraints in UK Housing market
It is estimated the UK need to build 350,000 homes a year to try and meet backlog of estimated 4 million homes. The UK has one of lowest ratios of homes to people in Europe.
More data on housing market supply and future population trends
Trends in housing tenure
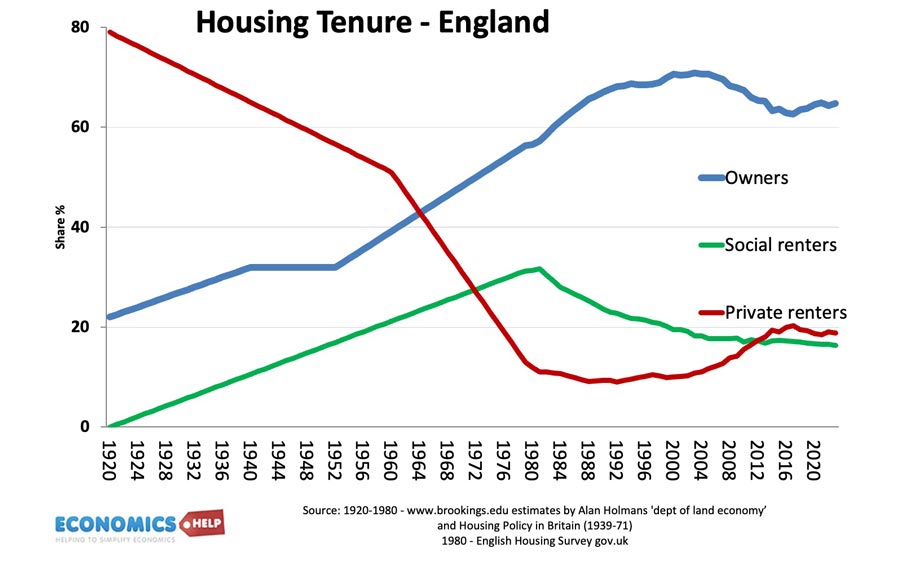
From 1920 to the end of the 1990s, there was a sharp rise in homeownership and fall in private renting. HOwever, since mid 1990s a rise in the cost of housing has seen a fall in home-ownership rates and rise in share of people in the private rented sector. Due to shortage of rented properties, rents have risen faster than inflation

This shows how decline in rental listings per branch, combined with rise in population led to sharp rise in rents.
See also: The Changing Nature of UK Rented Sector
Mrs Thatcher encouraged this trend in the 1980s, with a policy of encouraging home ownership and selling off council homes. Mrs Thatcher allowed the sale of council properties to their tenants. The stock of social housing has fallen since the early 1980s.

Renting is generally more expensive than homeownership
Renting sector

UK Housing compared to elsewhere
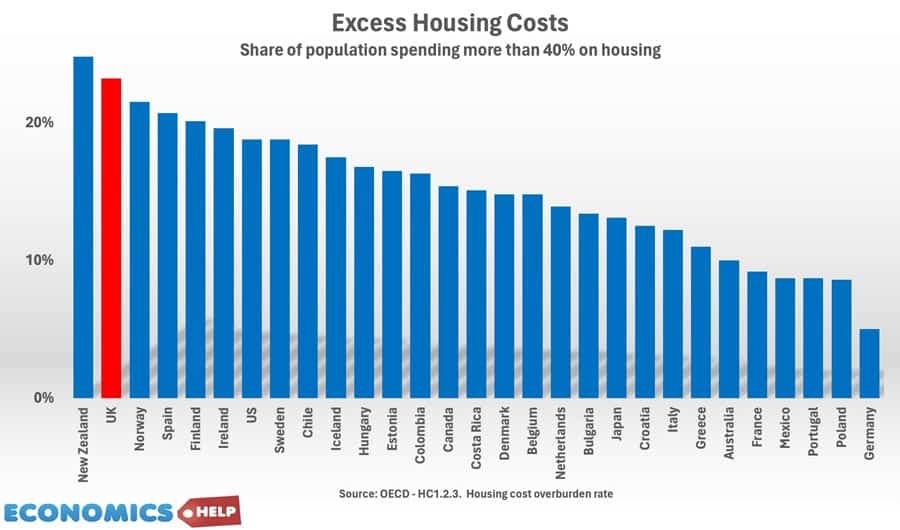
In terms of people facing excessive housing costs, the UK is one of most expensive countries in the world.
A collapse in mortgage lending post 2007 financial crash.
Homelessness
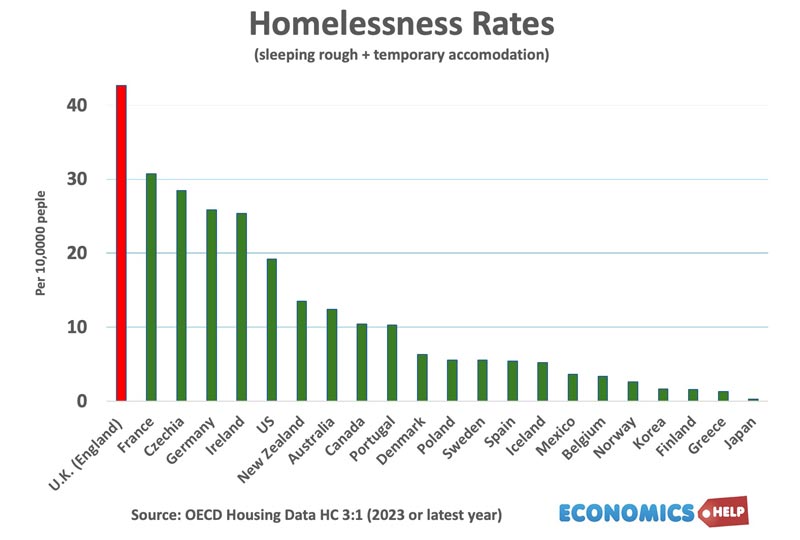
The high cost of renting means the UK has one of the highest rates of homelessness (defined as temporary accommodation)
Related
- Historical house prices
- Factors that affect housing market
- Housing Equity withdrawal
- Mortgage Calculator
About The Author

Is there any graphs on supply and demand in the housing market in recent years?
Regional house price graph is really useful.
It seems a average house price to average earning ratio of 5.1 times is the level at which we see prices topping out broadly speaking with the exception of london.
It would be interesting to see income levels versus rent levels and house prices, over say the last 10 years, but by city.
Great news for those looking to sell, but in many places it presents more of a barrier for anybody trying to move up the property ladder. How many people are now being priced out of these areas?
This is a very interesting study! It will be beneficial for those who are planning to buy properties in UK. They can now compare prices and trends in different places in UK.
As with a previous commenter, it would be interesting to see income levels versus rent levels and house prices, over say the last 10 years, but by city.
Using Bristol as an example, house prices have increased and rent levels have gone up way beyond what Housing Benefit will pay. As a result, rent is unaffordable – let alone deposits, and there has been a huge increase in homelessness applications.
However, since the number of local authority properties is declining, there are less options available. Resulting in 10,000 people on the waiting list for housing – and that’s after the city council culled 5,000 people that had ‘no chance’ of being successful in obtaining an LA property.
People are increasingly unable to afford to live in the city in which they work, as has happened with London. However, income in London seems to be adjusted to accommodate this when elsewhere income doesn’t seem to have increased to anywhere near enough to keep up.
Is the same thing happening in a city of a similar size such as Sheffield, Leicester or Derby. Are people being priced out of cities? Is there a difference in the economy growth rates between cities?