The new Bank of England governor, Mark Carney, has implemented a type of unemployment target.
As part of forward guidance, the Bank of England state that:
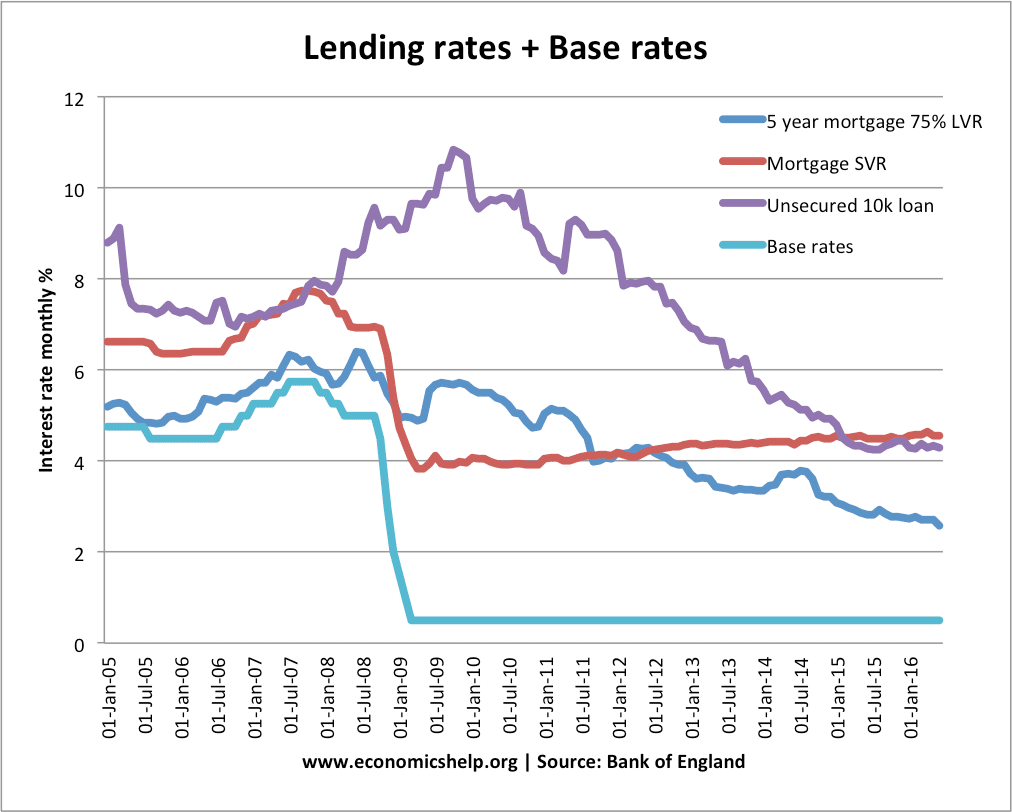
Interest rates won’t rise from 0.5% until unemployment falls below at least 7%.
Essentially, the bank are committing to expansionary (loose) monetary policy until there is a stronger economic recovery and unemployment has fallen. The hope is that the commitment to low interest rates will encourage firms to invest and consumers to spend.
However, this unemployment target of 7% has a few caveats. The unemployment target and forward guidance on interest rates can be ignored if:
- Inflation is forecast to breach a 2.5% target over a 24 month horizon.
- If there is a sharp rise in the public’s expectations of inflation
- If low interests are likely to imperil the stability of the financial system, e.g. low interest rates could fuel an asset bubble.
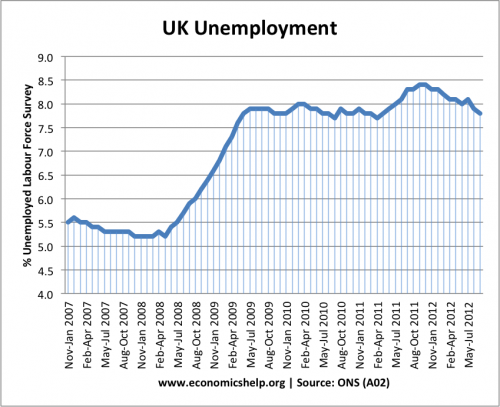
Under the Bank of England’s latest targets, it does not expect unemployment to fall below 7% until 2016. According to the ONS, unemployment is currently 7.8%. It would require the creation of nearly 750,000 new jobs for the rate to fall below 7%
Equilibrium Unemployment
The Bank of England also mentioned the term ‘equilibrium unemployment’. They believe the equilibrium unemployment rate is around 6.5%. The equilibrium rate means that if unemployment falls below 6.5% it might start causing inflation (e.g. competition for employers pushes up wages). If unemployment is above the equilibrium rate of 6.5% then there is slack in the economy (demand deficient unemployment) and this will keep inflation low.
This equilibrium rate of 6.5% is therefore composed of structural factors / supply side factors (the natural rate of unemployment)