The UK national debt is currently £2.9 trillion or 93.8% of GDP (21 May 2026). The public sector debt is the total amount of money the British government owes to the private sector and other purchasers of UK gilts (e.g. Bank of England).
- The OBR have forecast substantial rises in UK debt over the coming decade because of demographic factors, putting strain on UK spending.
- Source: [1. ONS public sector finances,- HF6X] (page updated 21 May 2026)

Source: ONS debt as % of GDP – HF6X | PUSF – public sector finances at ONS
Note: Revised down. In July 2023, ONS calculated debt at over 100% of GDP, but this has been significantly revised down. Debt lower than previous releases.
Reasons for Rising national debt
- Crisis Spending. Enables the government to spend more during periods of national crisis, e.g wars, pandemics, and recessions.
- Recession In a recession, the government will automatically receive lower tax revenues (less VAT and income tax) and will have to spend more on benefits (e.g. more unemployment benefits). This causes a cyclical rise in debt.
- Fiscal Policy Extra government borrowing during a recession can help provide fiscal stimulus to promote economic recovery. By borrowing and then spending more, the government is injecting demand into the economy and this can help to reduce unemployment.
- Political Pressures. Political pressures to cut taxes, increase spending make borrowing more politically appealing
- Spending commitments. UK welfare budget is rising because of growing number of pensioners, and rise in health-related benefits.
- Investment The government borrow to finance public investment projects that can hopefully lead to higher growth in the future.
Forecast for the National debt?
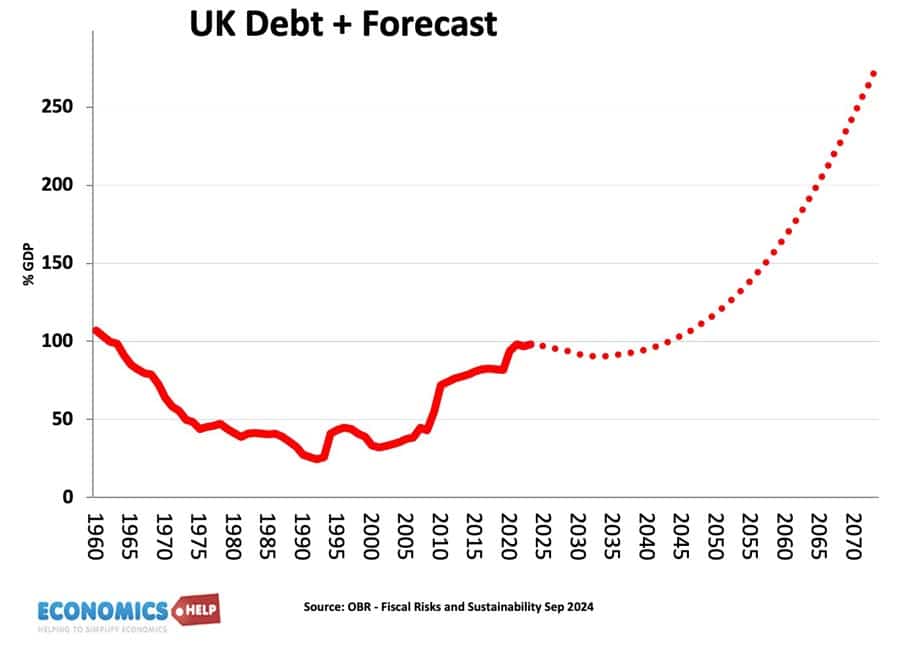
Source: Fiscal risks and sustainability – OBR – Economic and Fiscal Outlook Oct 2024
The OBR have forecast that, on our given trajectory, UK public sector debt could reach 350% of GDP within 50 years. The pessimistic outlook for national debt is made because:
- An ageing population and demographic changes will put increased pressure on government spending, notably health care and pension spending.
- A smaller working population will limit UK’s productive capacity.
- Stress on finances from geopolitical events, such as frostier relations with China, Russia and the Middle East.
- Higher energy prices
- Costs of climate change.
- Declining tax revenues from petrol in a decarbonising economy.
- Low productivity growth of UK since the financial crash of 2009
- Recent boost to debt from the financial crisis and one-off cost of Coronovirus pandemic, which cut tax revenues and required government support for lockdown measures.
UK debt in context
Predicting debt for the next 50 years is difficult since we don’t know what kind of productivity improvements may come, e.g. continued gains in renewable energy may reduce the burden of higher oil and gas prices. Equally, the costs of environmental change could be worse.
History of the national debt

Main article: History of UK national debt
UK national debt since 1900
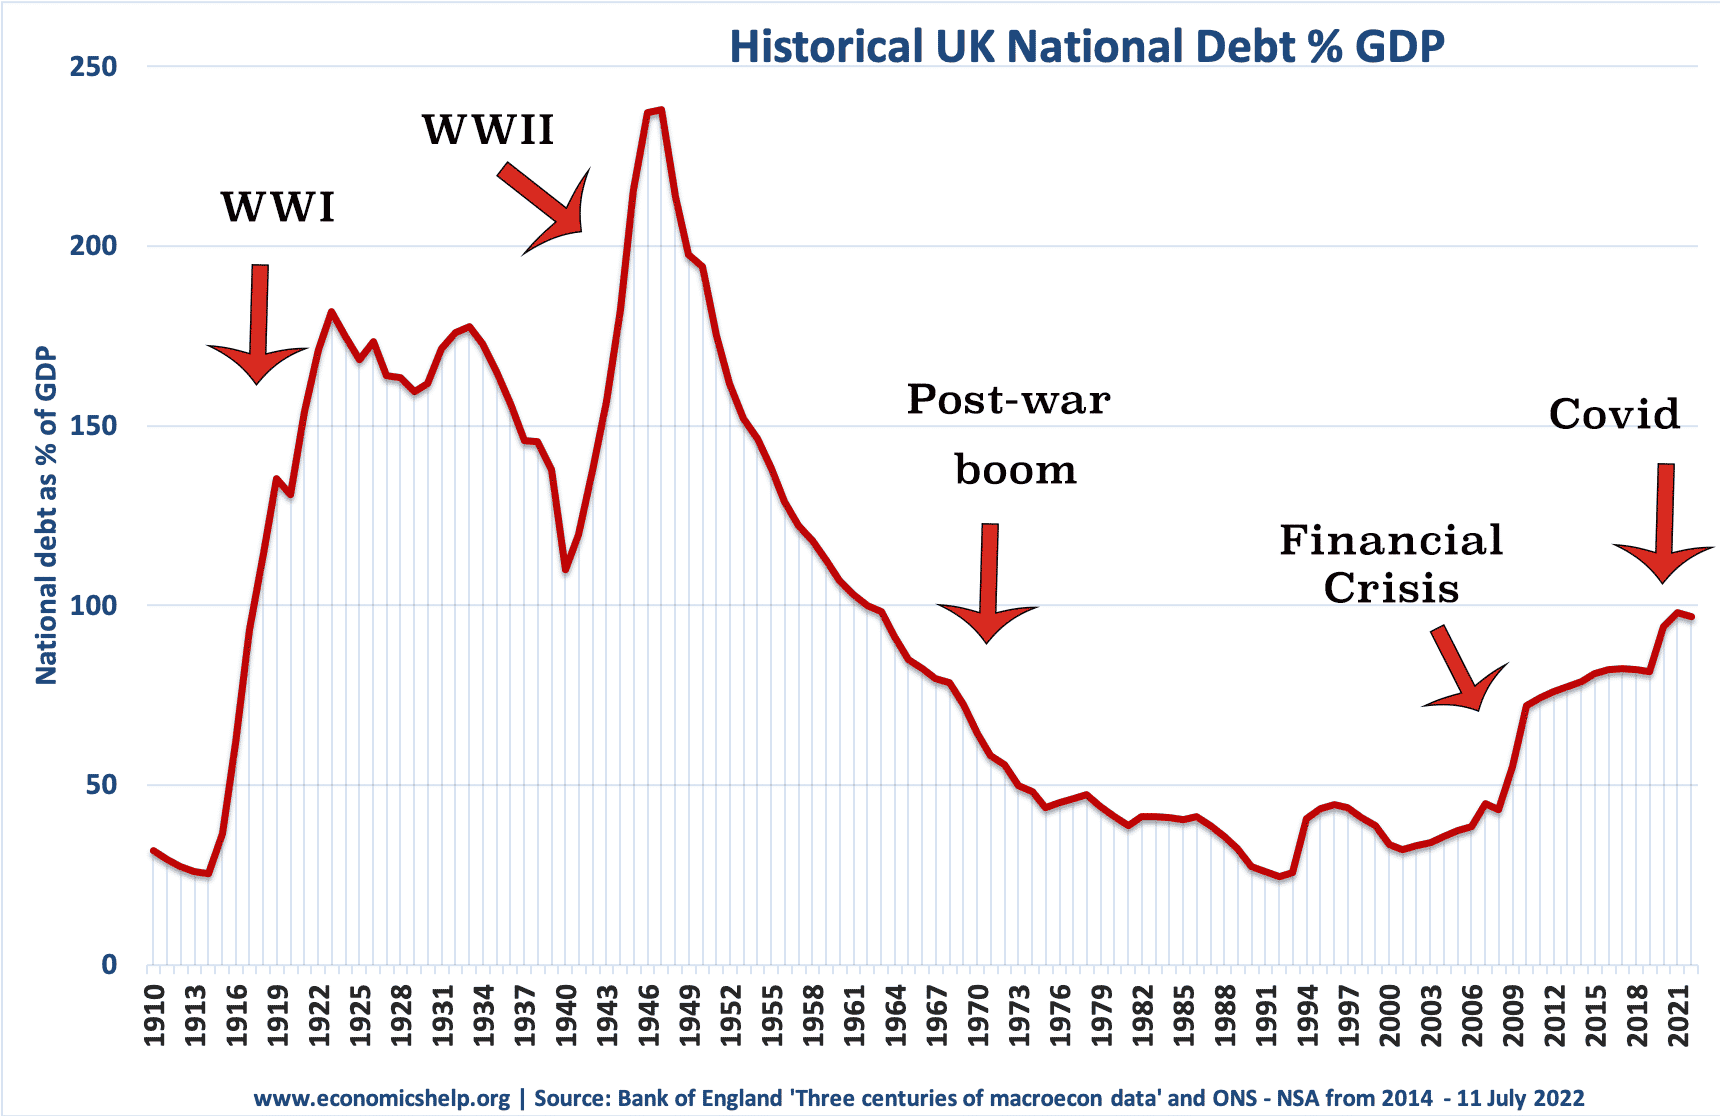
Source: Reinhart, Camen M. and Kenneth S. Rogoff, “From Financial Crash to Debt Crisis,” NBER Working Paper 15795, March 2010. and OBR from 2010.
These graphs show that government debt as a % of GDP has been much higher in the past. Notably in the aftermath of the two world wars. This suggests that current UK debt is manageable compared to the early 1950s. (note, even with a national debt of 200% of GDP in the 1950s, UK avoided default and even managed to set up the welfare state and NHS.
The post-war levels of national debt suggest that high debt levels are not incompatible with rising living standards and high economic growth.
- The reduction in debt as a % of GDP 1950-1980 was primarily due to a prolonged period of economic growth. See: how the UK reduced debt in the post-war period
- This contrasts with the experience of the UK in the 1920s when in the post First World War, the UK adopted austerity policies (and high exchange rate) but failed to reduce debt to GDP. Debt in Post-First World War period.
Debt reduction and growth
Budget deficit – annual borrowing
This is the amount the government has to borrow per year.
- Government borrowing in the financial year to December 2024 was £129.9 billion
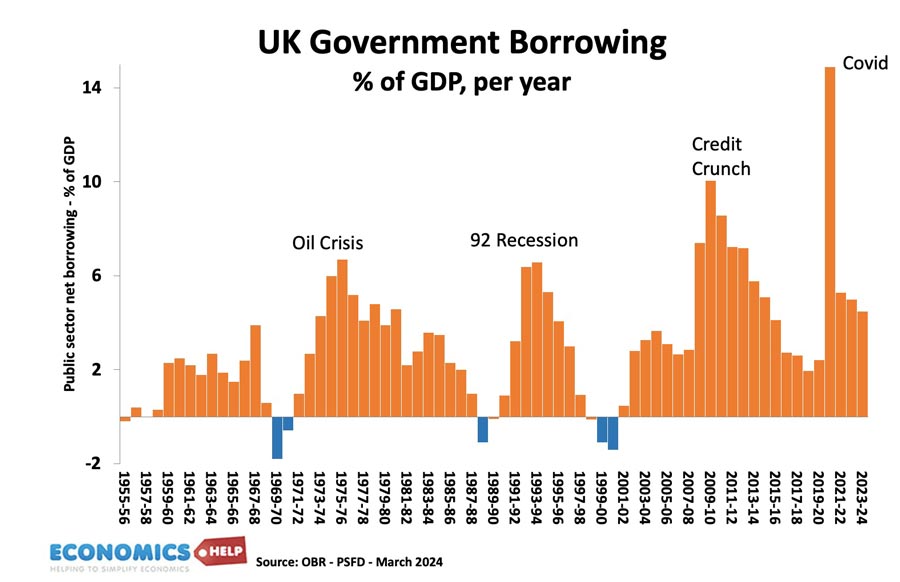
Annual borrowing since 1950. Figures for 2023-24 are forecasts (and rather optimistic!)
Debt and bond yields
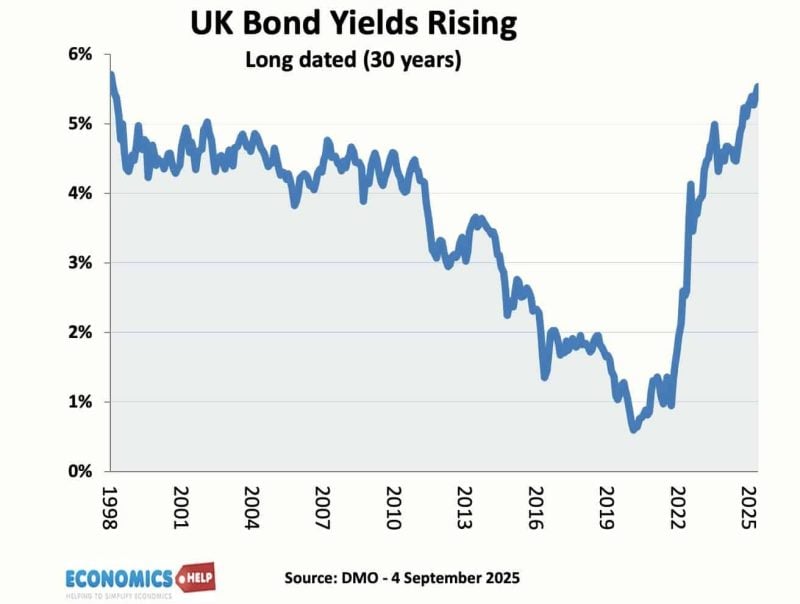
Bond yields are the interest that the government pay bond/gilt holders. It reflects the cost of borrowing for the government. Lower bond yields reduce the cost of government borrowing.
Between 2007 and 2020, UK bond yields fell. However since 2021, bond yields have risen due to:
- Higher inflation
- Higher interest rates (to try and reduce inflation_
- A premium for risk of UK default (or partial default through inflation)
Cost of Interest Payments on National Debt

The cost of National debt is the interest the government has to pay on the bonds and gilts it sells. According to the OBR in 2025-26, total debt interest payments will be £126 billion. (3.5% of GDP). It is lower than in previous decades because of lower bond yields.
See also: UK Debt interest payments
The era of low interest rates post 1992 helped to reduce UK debt interest payments as a ratio of government revenue. However, with interest rates and borrowing increasing – debt interest cost have increased significantly in recent years. They have now become the 4th largest source of UK government spending.

Problems of National Debt
- Interest payments. The cost of paying interest on the government’s debt is very high. In 202/25 debt interest payments will be £126 billion a year (est 3.6% of GDP). Public sector debt interest payments will be the 4th highest department after social security, health and education.
- Higher taxes / lower spending in the future.
- Crowding out of private sector investment/spending.
- Set to get worse The structural deficit will only get worse as an ageing population places greater strain on the UK’s pension liabilities. (demographic time bomb)
- Higher rates. Potential of rising interest rates as markets become more reluctant to lend to the UK government.
- Inflationary pressures. If debt is financed by Bank of England creating money to buy gilts, there could be an increase in inflationary pressures over time.
However, government borrowing is not always as bad as people fear.
- Borrowing in a recession helps to offset a rise in private sector saving. Government borrowing helps maintain aggregate demand and prevents a fall in spending.
- In a liquidity trap and zero interest rates, governments can often borrow at very low rates for a long time (e.g. Japan and the UK) This is because people want to save and buy government bonds.
- Austerity measures (e.g. cutting spending and raising taxes) can lead to a decrease in economic growth and cause the deficit to remain the same % of GDP. Austerity measures and the economy | Timing of austerity
- Investment in infrastructure could help long-term performance of the economy
Who owns UK Debt?

The majority of UK debt used to be held by the UK private sector, in particular, UK insurance and pension funds. In recent years, the Bank of England has bought gilts taking its holding to 25% of UK public sector debt.

Source: DMO Debt Management Report 2022/23
- Overseas investors own about 28% of UK gilts (2023).
- The Asset Purchase Facility is purchases by the Bank of England as part of quantitive easing. This accounts for 26% of gilt holdings.
Total UK Debt – government + private
- Another way to examine UK debt is to look at both government debt and private debt combined.
- Total UK debt includes household sector debt, business sector debt, financial sector debt and government debt. This is over 500% of GDP. Total UK Debt
Private sector savings
 When considering government borrowing, it is important to place it in context. From 2007 to 2012, we have seen a sharp rise in private sector saving (UK savings ratio). The private sector has been seeking to reduce their debt levels and increase savings (e.g. buying government bonds). This increase in savings led to a sharp fall in private sector spending and investment. The increase in government borrowing is making use of this steep increase in private sector savings and helping to offset the fall in AD. see: Private and public sector borrowing
Comparison with other countries

Although 101% of GDP is high by recent UK standards, it is worth bearing in mind that other countries have a much bigger problem. Japan, for example, has a National debt of 250% (though confusingly Japan net debt is lower because of large assets), Italy is 135%. The US national debt is 123% of GDP. [See other countries debt].
How to reduce the debt to GDP ratio?
- Economic expansion which improves tax revenues and reduces spending on benefits like universal credit. The economic slowdown which has occurred since 2010 has pushed the UK into a period of slow economic growth – especially if we consider GDP per capita growth. Therefore the further squeeze on tax revenues has led to deficit-reduction targets being missed.
- Government spending cuts and tax increases (e.g. VAT) which improve public finances and deal with the structural deficit. The difficulty is the extent to which these spending cuts could reduce economic growth and hamper attempts to improve tax revenues. Some economists feel the timing of deficit consolidation is very important, and growth should come before fiscal consolidation.
- See: practical solutions to reducing debt without harming growth
Sectoral Balances
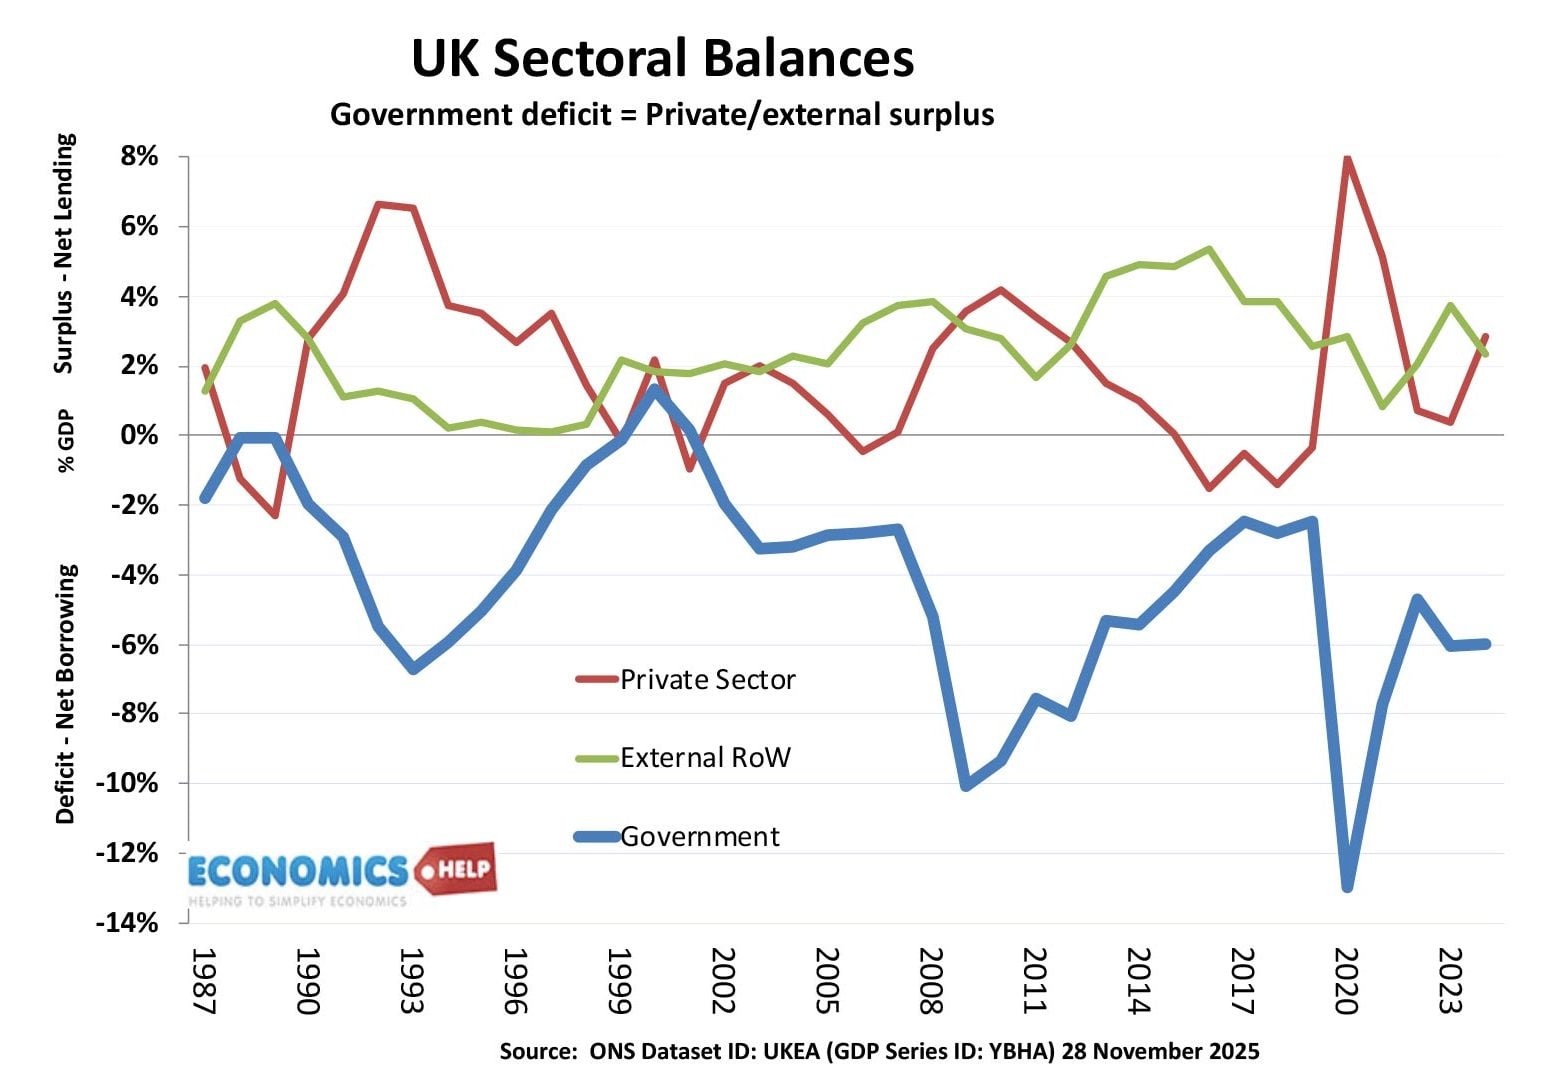
Government deficit is always matched by private sector or external surplus. For more explanation, see: Sectoral balances
Other countries debt
See also:
ONS stats on public sector debt
About The Author

The most common measure of National Debt is as percentage of GDP. However, to put debt into perspective, (as a non-economist), I suggest we also examine other figures such as:
1. Ratio of debt over government income £2,347.7 billion divided by £820 billion = 2.863
2. Debt per capita of the working population of 32.8 million.
Debt £2,347,700 million divided by working population 32.8 million = £73,365!